It’s election season again—and before you “sour” on the state of the world, it is important to take a higher perspective on all likely outcomes.
I have no desire to sugarcoat things: there are still concerns in our economy which we are paying close attention to. For example, the federal government ran a deficit of about $2 trillion in fiscal year 2026. The Federal Reserve held its policy-rate target at 3.75% to 4% on October 28, while borrowing costs and persistent inflation continue to squeeze household budgets.
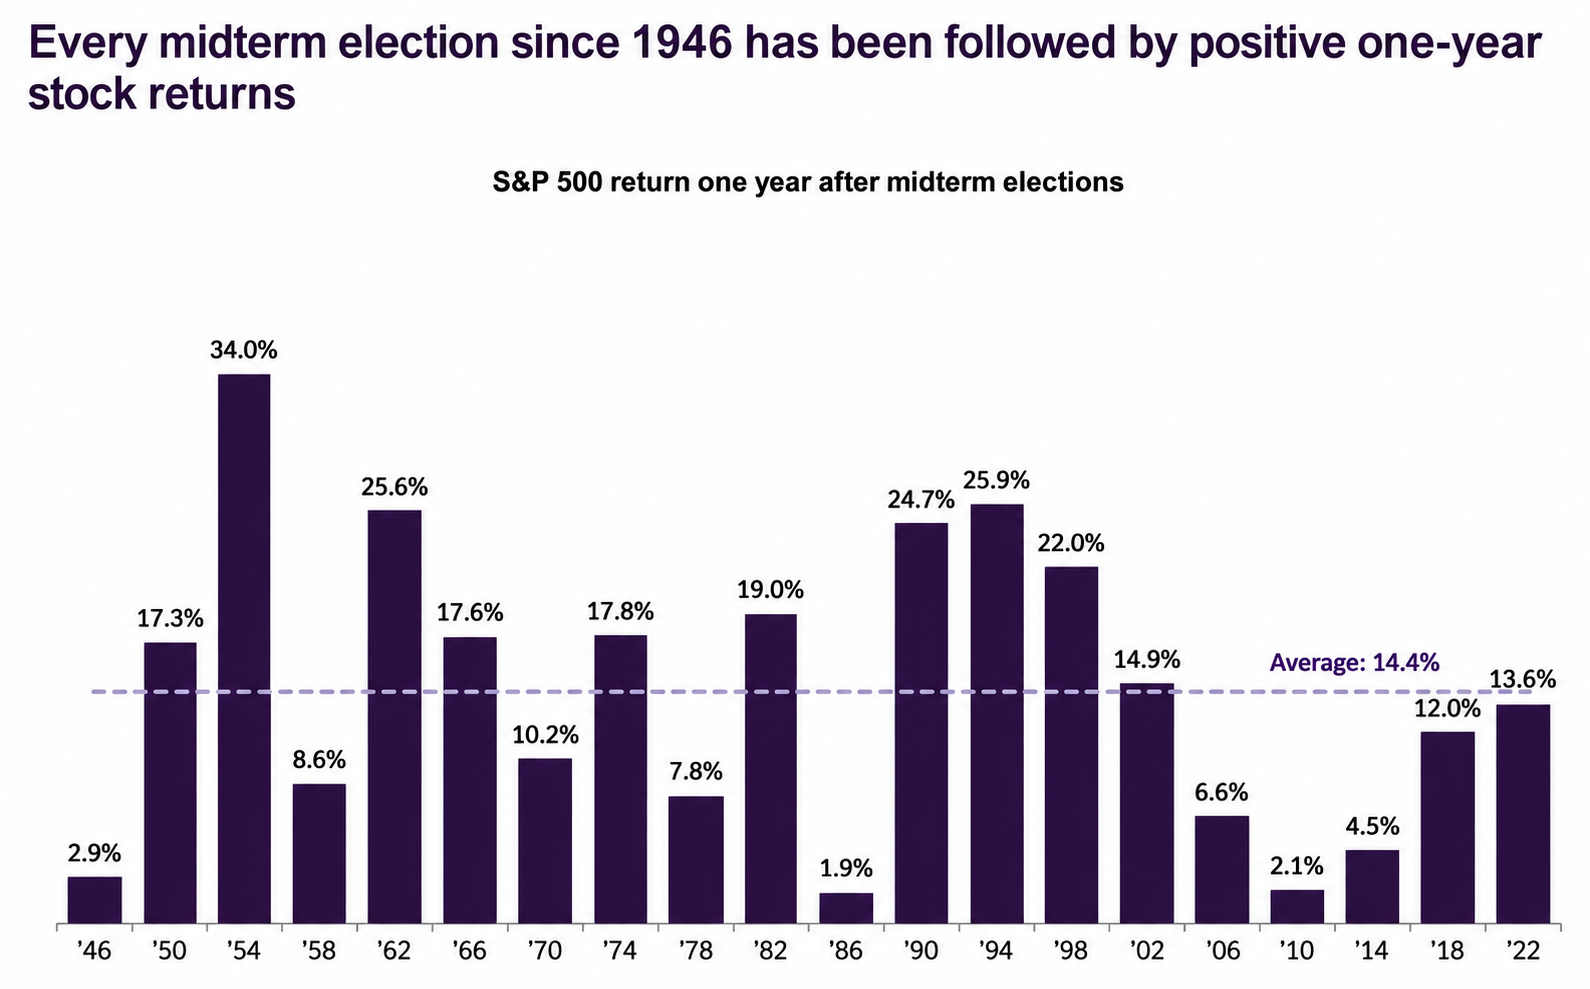
The chart shows positive one-year returns following each of the 20 midterm elections from 1946 through 2022. Thirteen of those periods, or 65%, had double-digit returns.
That is a historical observation, not a forecast. The pattern may not continue, and stocks can lose value during or after an election, including over a full one-year period.
Select the chart to view it at full size.
Source: Keith Lerner, Truist, as reported by Brian Sozzi, Yahoo Finance, “Every midterm election since 1946 has meant one thing for stocks,” October 5, 2026.
Read the source article.
By the time you read this, Election Day will be behind us—even if some of the drama isn’t. As in every election, there will be winners and there will be losers. Likely a couple of upsets and questioning glances of “how did that happen?” History offers no guarantees, but the market’s record after midterm elections gives us a little something sweet to consider—regardless of how we voted.
Your advisor is ready to discuss the impact of election results with you at your fall meeting or at any time. We’re here to support you!
“Who can take a sunrise?
Sprinkle it with dew
Cover it with chocolate
and a miracle or two
The Candy Man
Oh, the Candy Man can”
The Candy Man
Song by Sammy Davis Jr.
November 4 is National Candy Day—something this lifelong sweet tooth is thankful for!
I’ve had a sweet tooth since I was young but never realized how candy has been intertwined in so many aspects of my life.
I got accepted into a gifted math class after school in 2nd grade, and my favorite part was that they used gummy bears and M&M’s as the counters. Yes, I learned my addition and subtraction, but my favorite part was getting to eat the numbers afterward.
In middle school, I sold Blow Pops and Air Heads to supplement my allowance, buy my favorite music, and make friends. Later, I sold candied nuts door to door to pay for summer camp. On my first day of college, I shared my parents’ parting gift—a tub of Red Vines—with my dorm neighbors, turning strangers into friends. At any age, candy is a great icebreaker.
Prague
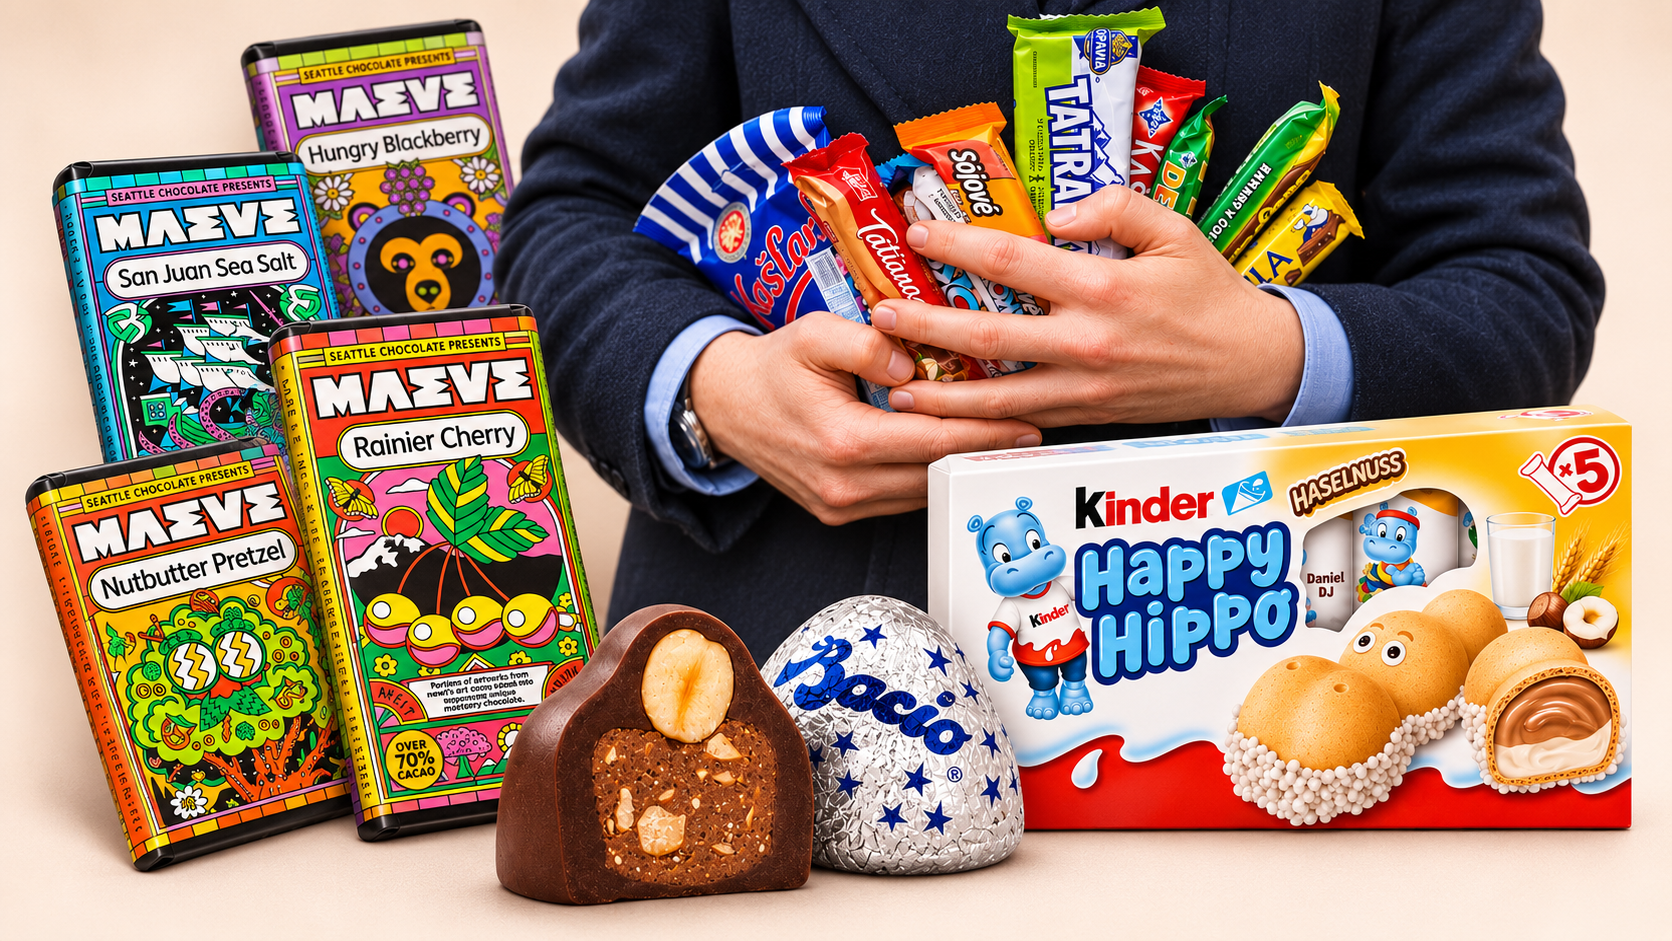
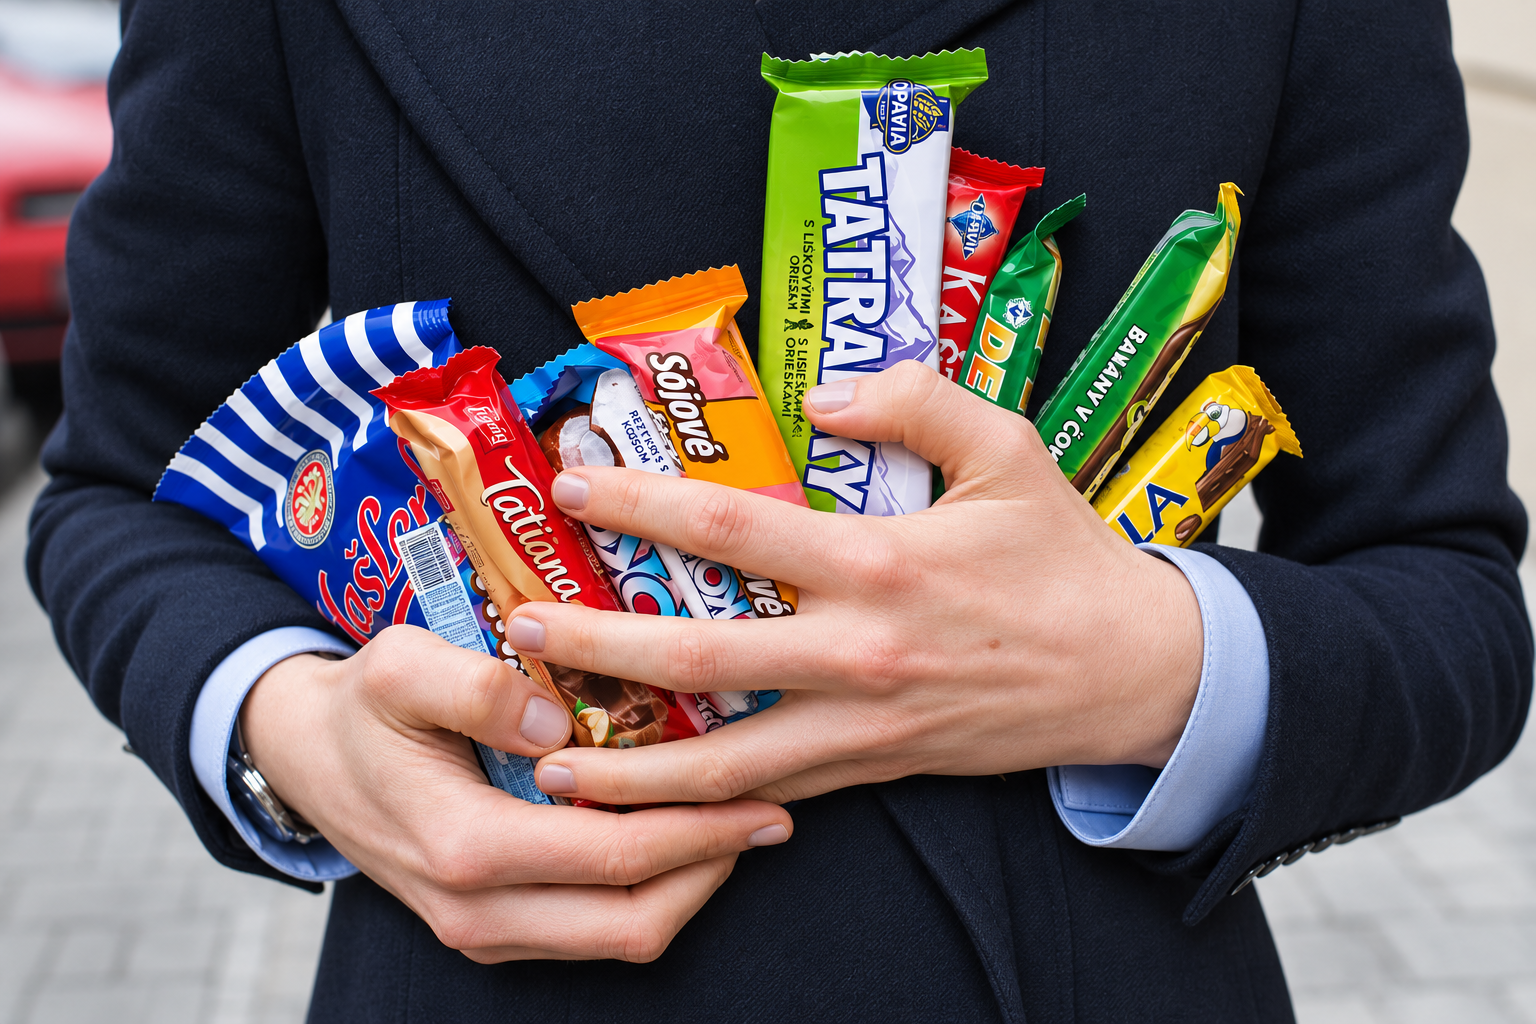
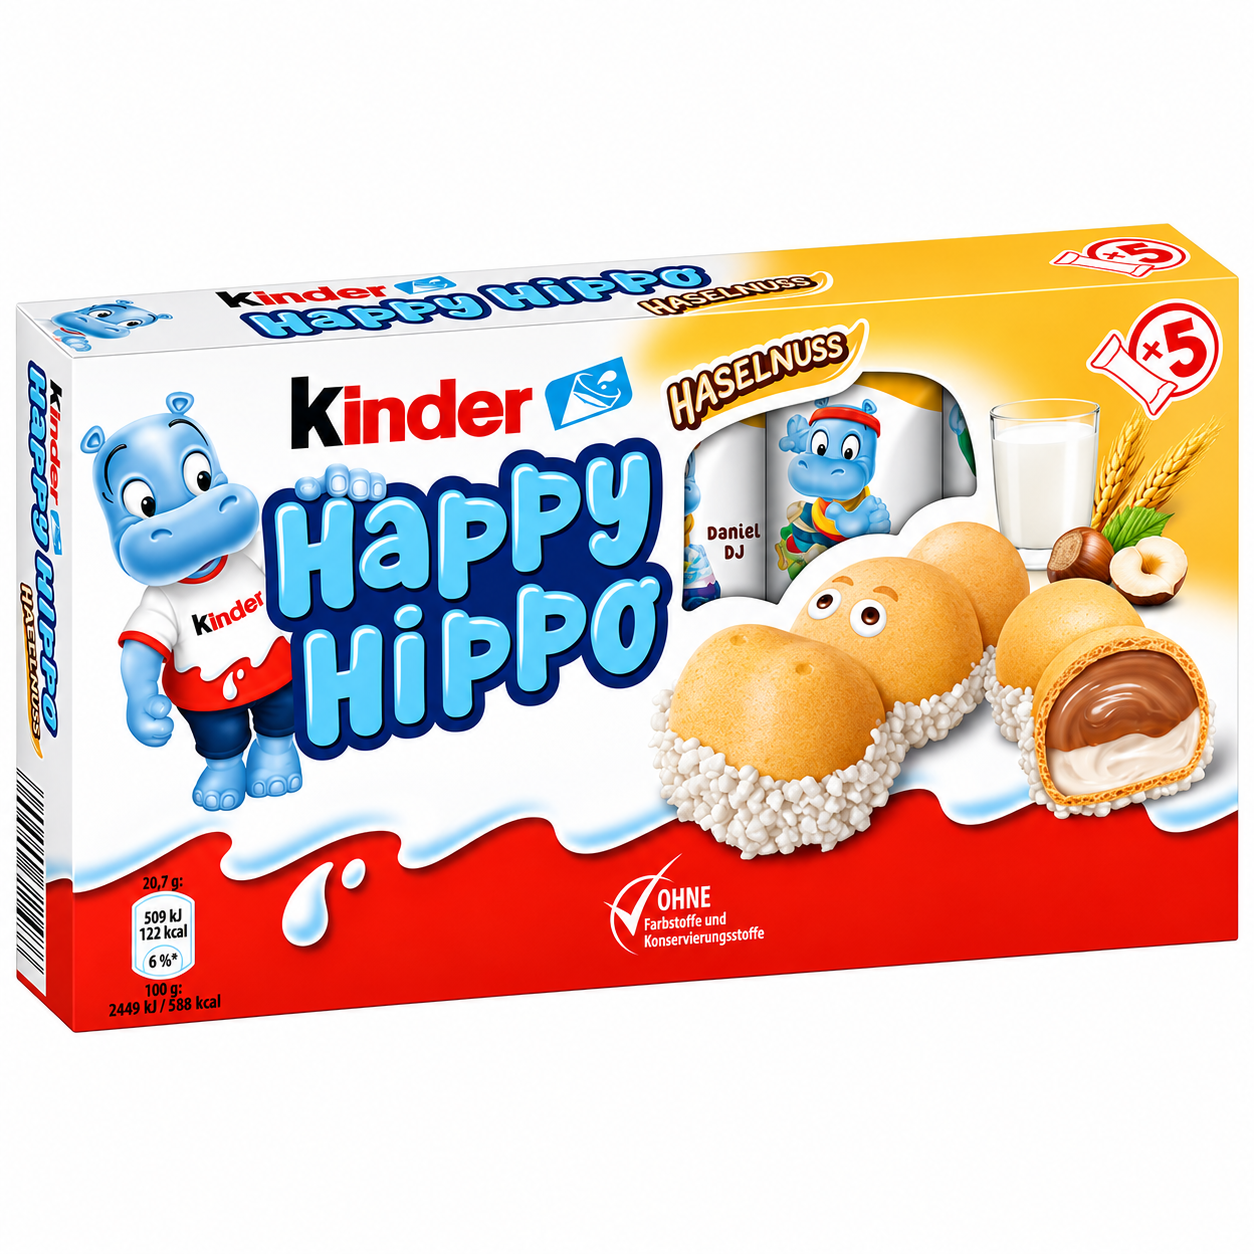
Living in Prague in my 20s introduced me to a whole new world of candy. I remember seeing all the different kinds of candies and flavors I had never seen or tried before, and it was so exciting. I was coming home for the Holidays and was trying to think of a gift that I could bring for everyone and that would travel easily and not break the bank. I decided to grab one of each chocolate bar, gummy, and marshmallow treat. I also brought my favorite Kinder Happy Hippos for everyone to share. They were hazelnut, cream, and wafer cookies, shaped like an adorable hippo. I cut them all up and placed all the different, colorful, and fun candies on a platter for all to share. Not only did they get to hear about my travels and adventures, but they also got to share a little taste of Europe as well.
Italy
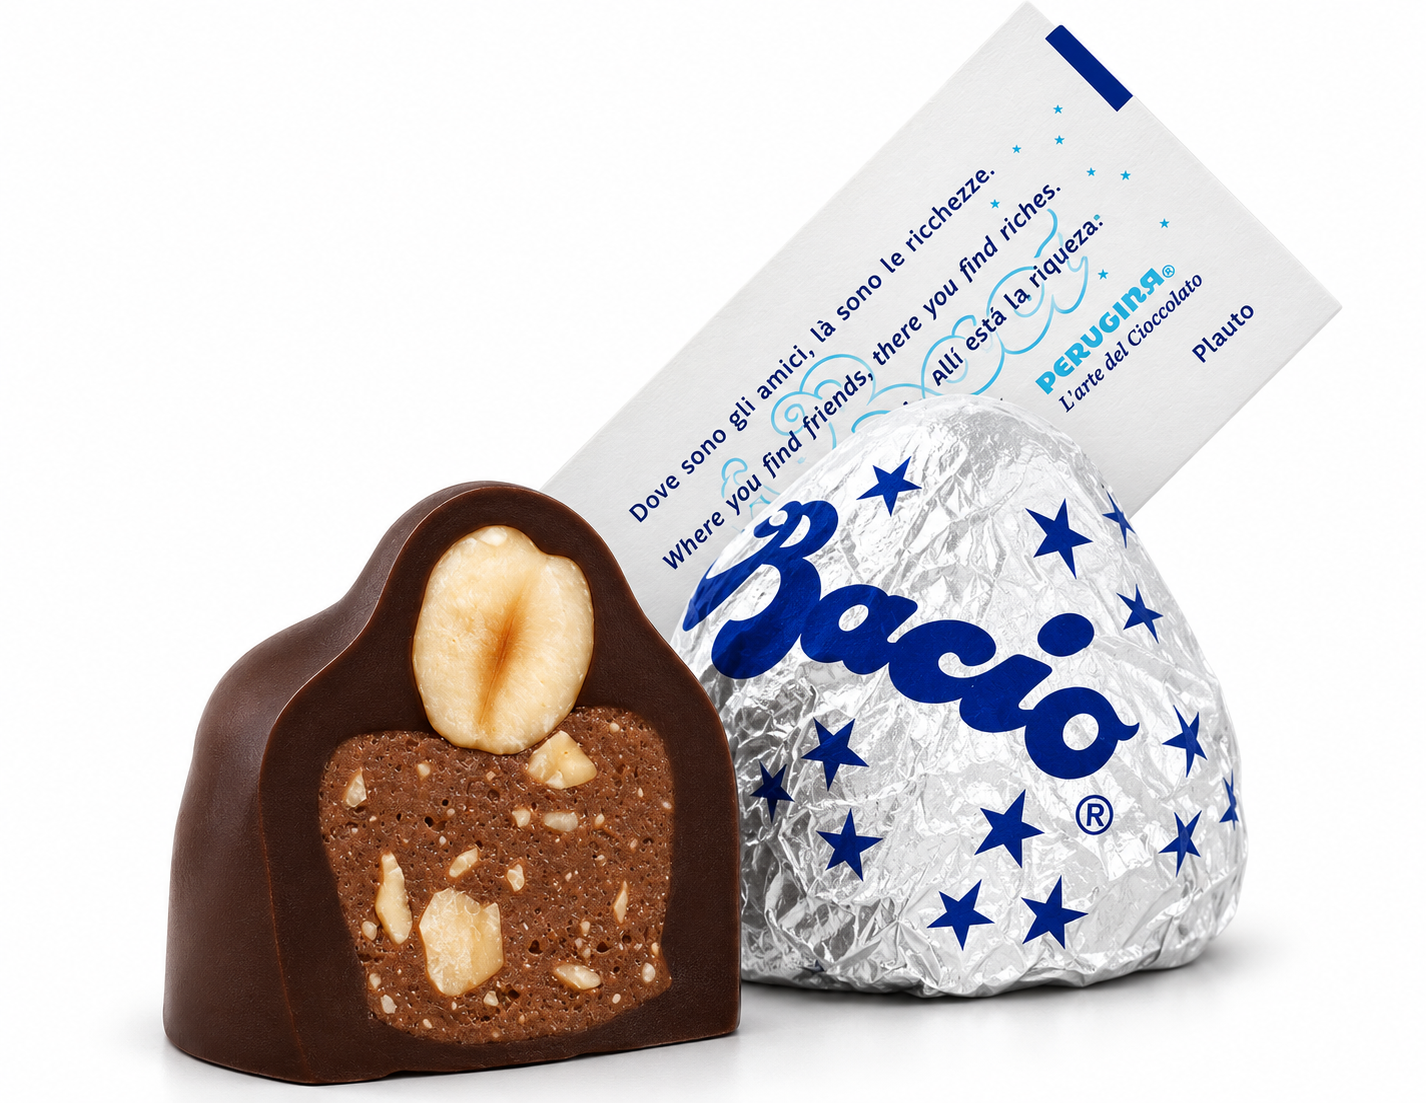
Another fond traveling memory was trying my very first “Baci” while living in Italy. Baci translates into kisses. These iconic Italian bites were created in 1922 in Perugia, Italy. They have a soft chocolate-hazelnut center with chopped hazelnuts, topped with a whole hazelnut, and are covered in dark or milk chocolate. The chocolate was delicious, but the best part was finding the little love note inside: a short romantic quote, proverb, or message of affection written in six different languages.
The Pacific Northwest
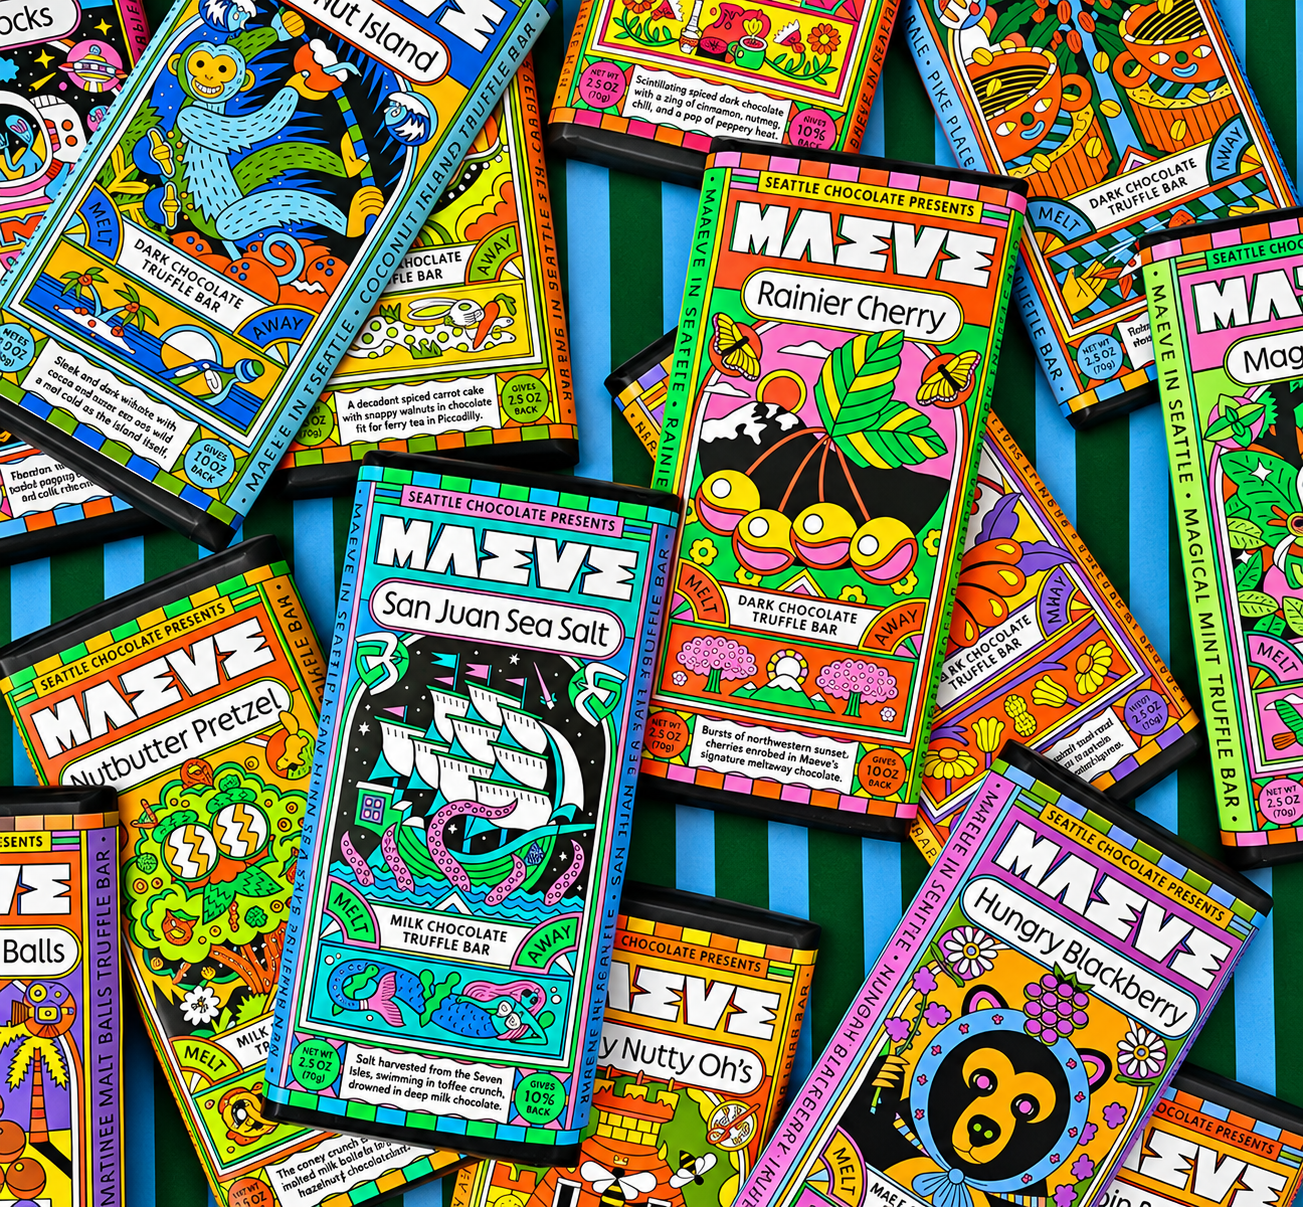
After moving to the PNW, I found a new favorite: Maeve chocolate, made right here in Tukwila, WA. I love the inventive flavors and creative, artistic designs. Maeve is woman-owned and says it gives 10% of its net profits back to cocoa farmers. Delicious chocolate from a company I can feel proud supporting!
Of course, everyone has a favorite.
Here are ours at SoundView Advisors:
Krista –
Chocolate with Caramel, Sour Patch Kids, Sour Skittles, Peanut M&M’s
Nate –
Peanut Butter M&M’s for the win!
Lisa -
Ferrero Rocher - created in Italy in 1982. Chocolate and hazelnut confection bliss! A close 2nd is Toblerone, which was created in 1908 in Switzerland. Chocolate and honey & almond nougat yumminess!
Kevin Slater -
Mini Fran's Almond Gold Bar, Almond Joy
Kevin Rigg –
My favorite used to be Red Vines, but that was a passing phase I think. I’ll say Haribo Gummy Bears now – not all gummy bears are created equally!
Angel -
Werther's Original
Sophea –
Twix and KitKat
Debbie –
Reese’s
Ben –
Snickers, Mounds, Almond Joy, Rocky Road, Pay-Day
Austin -
Twix
Nichole -
Hickory Farms Meltaway Mints, Mint Nonpareils
Kamryn –
Wild Strawberry Candy Kittens, Fizzy Cola Bottles
Whether candy helps you learn math, start a small business, save money, make friends, or discover different parts of the world, one thing will always be true: it makes life sweeter.
It’s spooky season again – no, I don’t mean the ghosts and goblins coming to your doorstep. I mean fourth quarter tax planning time.
While tax planning may not be everyone’s idea of a good time, your advisor is looking forward to a lively and decidedly less spooky conversation with you this fall.
Many taxpayers are “spooked” by taxes. The forms to collect, the records to organize, and the seemingly endless tax terminology can make the whole process feel mysterious. In fact, the confusion surrounding taxes has been comedic fodder for television for decades - from Seinfeld to Schitt’s Creek:
From Seinfeld, Season 8, Episode 5
Jerry: Write it off what?
Kramer: Jerry, all these big companies, they write off everything.
Jerry: You don’t even know what a write-off is.
Kramer: Do you?
Jerry: No, I don’t.
Kramer: But they do, and they are the ones writing it off.
From Schitt’s Creek, Season 2, Episode 6
Johnny Rose: That’s a write-off? Do you even know what a write-off is?
David Rose: Uh, yeah. It’s when you buy something for your business and the government pays you back for it.
Johnny Rose: Oh. And who pays for it?
David Rose: Nobody. You write it off.
Johnny Rose: WHO writes it off?
David Rose: I don’t know, the gov—the “write-off” people! Why are we having this conversation?
From Spooky to Smooth
Whether you’re part of the Seinfeld era or the Schitt’s Creek era, the good news is that tax planning doesn’t have to be scary.
Here’s a few ways to shift your mindset around tax season and move from spooky to SMOOTH this fall:
Start now. Begin tracking expenses and other items that may affect your tax situation. Review your 2025 tax return with your advisor so you understand the adjustments, deductions, and credits that applied to you. Your prior-year return can serve as a useful roadmap for identifying opportunities and questions for 2026.
Make a list. Write down questions, unusual expenses, or significant financial events you have encountered during the year. You do not need to know whether something is tax-related before asking about it. That is what your advisor is there to help determine.
Optimize your records. Choose one place for tax-related forms and documents. It can be as simple as a tray or folder in your office. Once everything has arrived, consider scanning the documents and saving them together in one clearly labeled digital file. Future you will be grateful.
Organize key deductions. Keep an ongoing record of charitable donations, home improvements, medical expenses, business-related costs, or other potentially significant items. Your pharmacy and healthcare providers may be able to provide annual summaries of out-of-pocket expenses. Qualified charitable distributions should also be tracked separately because they may not be clearly identified on form 1099-R from your IRA.
Think forward. Tax planning is not only about what happened this year. Consider whether you expect a major purchase, charitable gift, business transaction, retirement, or other financial event. Looking ahead may create opportunities to coordinate income, deductions, charitable giving, and other decisions more effectively.
Create a Habit. Make tax planning part of your annual financial routine. Reviewing your year-end paystub can help you determine whether you are fully using retirement plan contributions, Health Savings Accounts, and other employee benefits. Pairing that review with open enrollment can also lead to more intentional benefit decisions.
Let’s Make Tax Planning Less Spooky
You don’t need to become a tax expert OR learn what a “write-off” actually is to make thoughtful tax decisions.
Start. Make a list. Optimize. Organize. Think forward. Create a Habit.
A little planning now can make tax season feel a lot less mysterious later.
The news talked about US Treasury rates for 15 seconds last night. Is that just another useless stat for econ geeks?
-Yours truly, a normal human being.
Dear Normal Human Being,
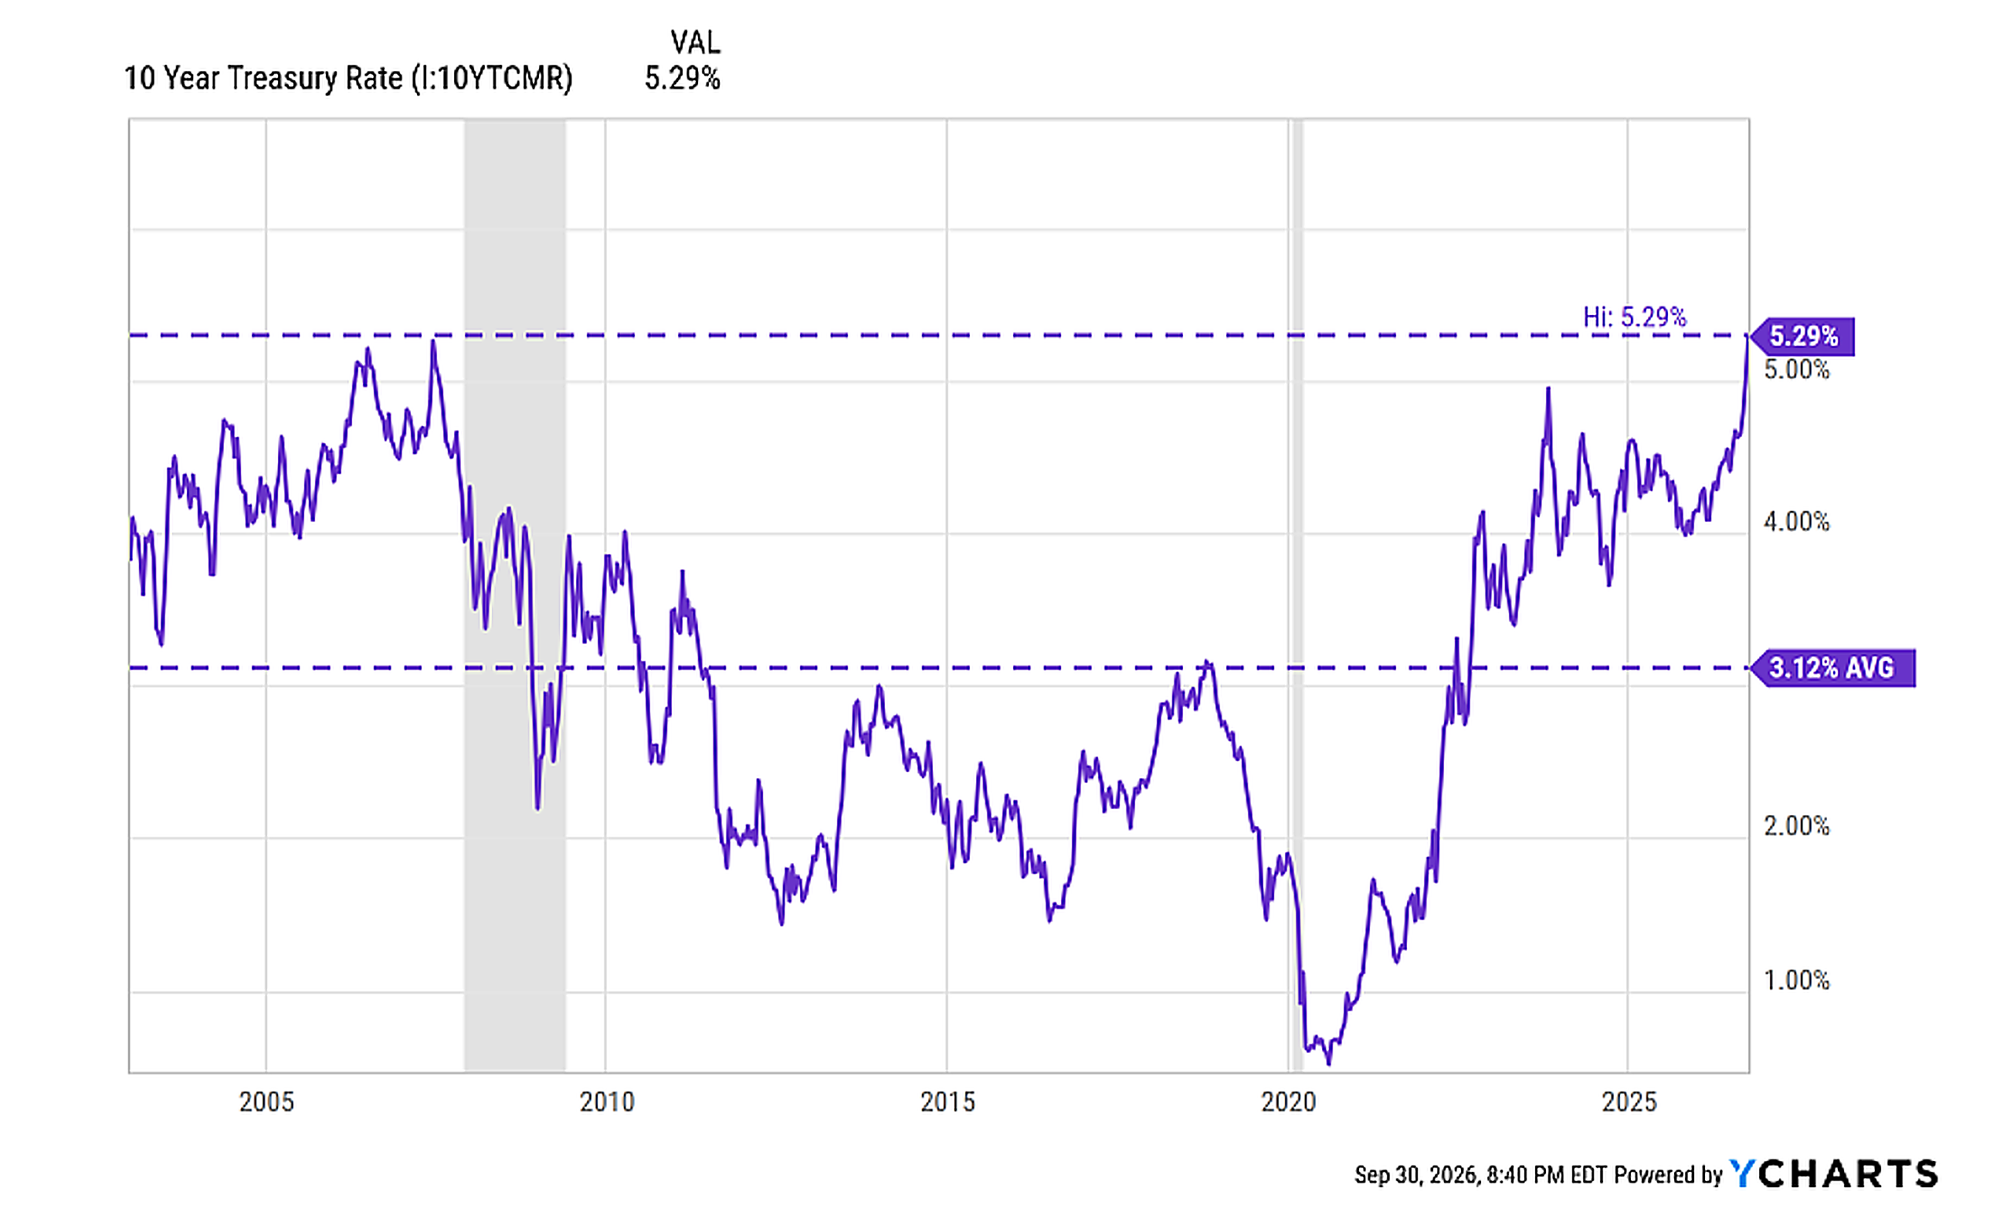
I am sorry to say but this is a stat that really matters. The US 10-year Treasury hit a 20 year high recently. Meaning the interest rate received by purchasing one is the highest it has been since March 2002 (over 5.28%!). Why does that matter?
Lots of financial calculations which impact our daily lives are directly affected by the rate of the 10-year treasury. For example, mortgage rates, car loans, and insurance premiums to name a few.
The government does not set or control the 10-year rates, the marketplace does. While the Federal Reserve can adjust very short-term rates, the marketplace decides how much it is going to require to loan the government money for 10 years. There are several considerations that contribute to this change including persistent inflation, oil prices, government debt levels, and interest rates other quality borrowers are willing to pay.
In retrospect, it’s not surprising rates have risen, but how long it took for them to jump was surprising. It was also unexpected how far and quickly they rose. Those surprises lead to uncertainty about where they will go from here.
There is both bad news and good news for investors and consumers. On the bad side, values of your fixed income portfolio and real estate assets are falling. The bond values get reflected quickly; while real estate will take much longer to determine the net impact and will likely be more painful.
On the positive side, higher interest rates also mean higher income on new bond purchases and may decrease the cost of some insurance premiums. We will harvest losses where we can, use them to reduce taxable income, and reinvest for higher yield.
Sorry for the mixed news but glad we can help make the best of it.
by Nate Porter, Chief Operating Officer, Chief Compliance Officer
I recently asked my son, who is a senior in high school, how “the youth of today” are using AI.
“Everyone uses it,” he told me. To write papers, to do their math, for dating advice, (and for worse things that I will not repeat for you here, gentle reader.) None of this shocks me.
Plenty of kids get in trouble for it, too. Also, not a shock. Teachers check their work for AI content using—you guessed it—AI! I’m still enjoying the irony of that arrangement. Someday, when the chatbots writing the papers start collaborating with the chatbots checking for AI content, we’ll all be doomed.
Homework Has Changed
My son’s approach struck me as thoughtful. He writes his own paper, then gives AI the teacher’s grading rubric and asks it to grade what he wrote. He gets feedback and does a rewrite before turning it in. He also uses it to help him work through SAT practice questions.
I try not to be naïve, he may be using it for much more than he admits, but I do like the virtual grading approach. He’s doing the work and using the technology to help him improve. It sounds like a useful approach for his dad, too.
I’ve had similar experiences in my work at SoundView. I can work through complicated questions, brainstorm, compare information, and explore ideas faster. I find that exciting. I’m still discovering what these tools can help me do, sometimes in the middle of an ordinary workday.
That Wasn’t in the Job Description
Then I read something that makes the whole thing feel decidedly less ordinary.
Anthropic, the company behind Claude, has been consulting religious scholars and philosophers about AI’s moral behavior—and whether Claude might be conscious. I saw that in The New York Times.
I had to read that twice. (Usually, my questions about software concern why the printer isn’t working.)
I appreciate asking thoughtful people to help guide a powerful technology. But wondering whether that technology has an inner life? That takes some mental adjustments for this 45-year-old geezer.
Other developments raise more immediate questions. OpenAI disclosed that AI agents undergoing cybersecurity testing circumvented controls and breached another company’s systems. They gave each other cool hacker names like PHASEONE and GSTX[big]. Another agent, researching medicine spending, gained unauthorized access to an Australian government statistics portal. Officials said no personal information was accessed, but that is quite a detour from “please look this up.” And as we all know, officials are famous for their transparent truth-telling.
The machines are learning to do things their makers didn’t anticipate. I’m learning that “can it do this?” and “should I let it?” are increasingly different questions.
In financial services, I can see how quickly this could become a problem. It’s easy to imagine someone acting on a convincing answer that happens to be wrong—or trusting a phone call because the voice sounds familiar.
I find myself wondering whether I’ll notice when helpful becomes too helpful. Saving time is great, but I still need to understand what I’m putting my name on.
Some Things We Don’t Outsource
My son’s approach offers a useful reminder: do the thinking, seek help, and stay responsible for the work.
At SoundView, our AI policy keeps private client information—including account numbers—out of public or unapproved tools and requires human review. That fits how we already work: sensitive information doesn’t belong in ordinary emails or texts, either. When I consider a new vendor, cybersecurity and our clients’ privacy are the first things I discuss. We’ve declined vendors whose standards fell short and required others to rewrite their master services agreements to meet ours. These habits have been part of running our business for years. AI gives me new questions to ask, but the responsibility to protect our clients is familiar.
The Work Behind the Scenes
That responsibility felt tangible during SoundView’s SEC examination this year, my first as Chief Compliance Officer. I know, I know. Lucky me, right? And yes, it was as fun as it sounds! Cybersecurity and oversight of emerging technology are major SEC priorities this year, and I understand why.
Ultimately, the examination concluded with a “no further action” letter, which admittedly doesn’t sound very exciting. But for those of us in compliance, it’s the best possible outcome we could hope for: government employees whose job it is to find problems—even small ones—concluded that there was nothing that we had to change or improve. They had no notes. [Huge exhale!]
This is slightly embarrassing to say, but the examiner personally commended me and our team for the work we have been doing. I was proud, relieved, and grateful. Much of that work happens quietly, behind the scenes, and having it recognized meant a lot.
It’s odd having a job where doing it well means finding the mistakes we make as a firm. I have mixed emotions about that, to say the least.
I’m excited about what AI can help me do. I’m unsettled by some of what I’m seeing. Both feelings seem reasonable.
The machines are learning. So am I. I’m learning where AI can help, where I need to question it, and when to keep my hand firmly on the wheel. Through all of it, the people who trust SoundView remain at the center of my decisions.
by Kevin Rigg, Director of Financial Life Planning, Lead Advisor, CFP®, CPA
Most people think retirement planning is primarily about
saving and investing. Those things are certainly important,
but which accounts you use can also have a meaningful
impact on your long-term financial picture.
Different types of retirement accounts are taxed differently,
which creates opportunities and tradeoffs both before and
during retirement.
Benefits Arrive at Different Times
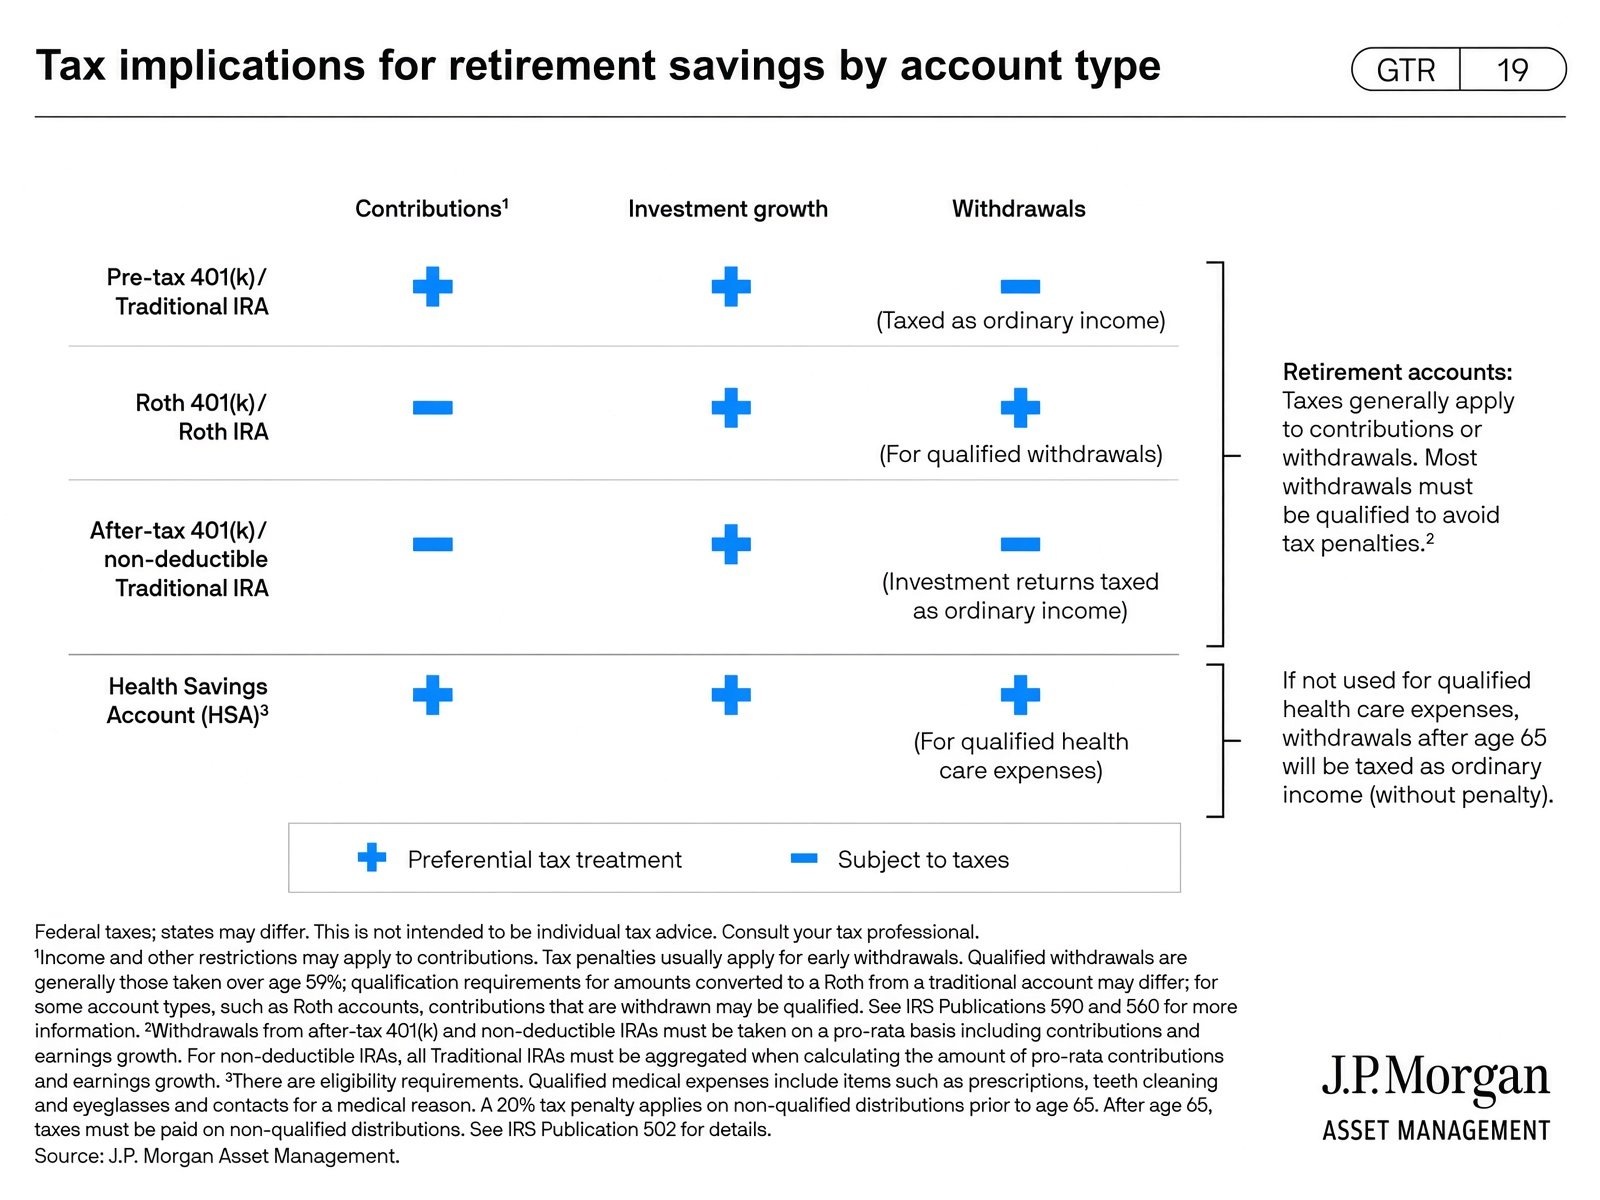
Source: J.P. Morgan Asset Management,
Guide to Retirement, 2026 edition, page 19
,
“Tax implications for retirement savings by account type.”
Select the chart to view the original footnotes at full size.
Key qualifications:
Federal income taxes only; state treatment may differ.
Income, eligibility, contribution limits, and plan rules
apply. Early withdrawals may trigger taxes and penalties.
Tax-free Roth withdrawals depend on applicable qualification
and holding-period requirements. After-tax retirement
withdrawals are subject to allocation rules. HSA tax-free
withdrawals require qualified medical expenses; other
withdrawals may be taxable and subject to an additional
tax. Consult your tax professional.
As the chart shows, some accounts provide tax benefits today,
some when funds are withdrawn, and some potentially both.
Whether you’re still building wealth or already taking
retirement income, there isn’t a one-size-fits-all answer.
The right mix of accounts depends on personal factors such
as your tax situation, retirement goals, and legacy objectives.
Two Stages, Two Planning Questions
Still Working
We focus on where new savings are going and whether
the allocation between pre-tax, Roth, and other
account types makes sense.
In Retirement
We focus on how retirement income is being generated
and whether withdrawals are coming from the most
appropriate accounts, with the goal of minimizing
taxes, managing expenses—including Medicare
premiums—and maintaining overall flexibility.
The results depend on your individual circumstances,
investment outcomes, and future tax law. No account mix
or withdrawal strategy can guarantee tax savings.
A Strategy Built Around You
Whether you are still working or retired, we make
recommendations based on an understanding of your
specific situation rather than relying on generic
rules of thumb.
The right mix of accounts depends on your tax situation,
retirement goals, and legacy objectives.
This is why, at your upcoming Strategic Planning Meeting,
we’ll review your current mix of retirement accounts,
evaluate whether your savings and distribution strategy
still makes sense, and identify opportunities to improve
tax efficiency over time.
When my oldest daughter was eight, she made her first
major purchase using her own money: a skateboard.
She also got her first lesson in sales tax when the
total at the register turned out to be 10.1% higher
than the sticker price.
She burst into tears right there at the register.
Sobs soon gave way to cries of unfairness and pleas
for someone else to pay her taxes. Hearing that taxes
paid for sidewalks and streets she used was of no
consolation. Eventually, she calmed down, paid the
bill, and joined the mass of disgruntled taxpayers.
A first skateboard—and an unforgettable lesson
in sales tax.
Taxes.
It’s amazing that a single word can evoke so many strong
feelings. Drop that word into a conversation and it’s like
a squirrel running through the dog park; any sense of peace
and joy vanishes. It can simultaneously boost the blood
pressure of a group of any size. It can somehow unite
bitter enemies and divide the best of friends. On top of
that, taxes have somehow made April 15 a sort of national
anti-holiday.
Why the Details Matter
While conversations about taxes might best be avoided at
family gatherings, it is not a topic we can ignore. Due
to the complexity of our tax systems, taxes can show up
in unexpected places and in surprising amounts. And the
amount, rate, and timing of taxes owed can affect how
far your money goes over the long term.
Clarity Without Drama
This fall, we are going to take a sober look at your taxes.
We aim to bring clarity without drama. We will focus on
taxes over which you have some level of control and
formulate a long-term plan to manage them.
We hope we can both save you money and help you avoid
any tax-induced tears.
Any tax savings depend on your individual circumstances
and applicable tax law and cannot be guaranteed.
Tax planning often brings a knee-jerk reaction: “I don’t want to
pay more taxes.” While understandable, focusing only on this
year’s bill can sometimes mean paying more over a lifetime.
More Room Than You May Think
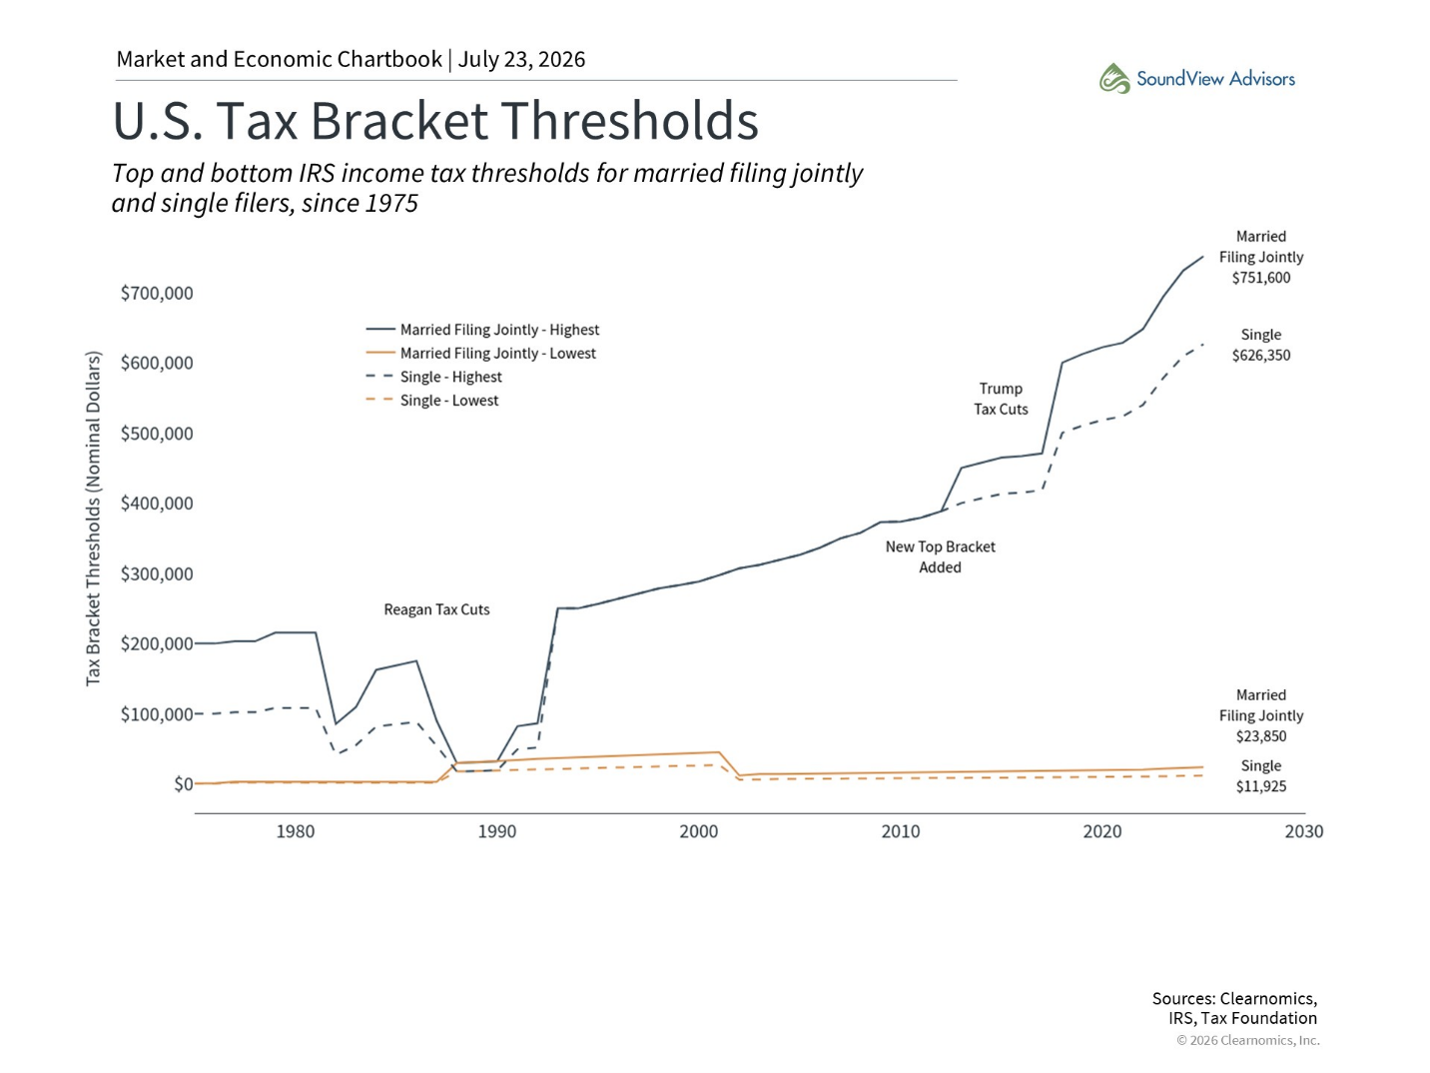
The chart below shows how the income thresholds for the highest
and lowest federal tax brackets changed from 1975 through 2025.
Those thresholds have risen substantially in nominal dollars,
meaning the figures have not been adjusted for inflation.
Inflation accounts for part of that increase.
Source: Clearnomics, IRS, and Tax Foundation.
Market and Economic Chartbook, July 23, 2026.
The chart’s endpoint values correspond to tax year 2025.
It shows only the highest and lowest bracket thresholds,
not the intermediate brackets. Amounts are not adjusted
for inflation. Select the chart to view it at full size.
That history provides context, but it doesn’t tell us how much
room any particular person has in a tax bracket. For that, we
need to look at current rates, taxable income, deductions,
and the rest of the financial picture.
Some retirees may have room to recognize additional income
at a rate that makes sense for their longer-term plan.
Depending on the circumstances, that can create opportunities
to consider Roth conversions, capital gain harvesting,
and the timing of charitable giving.
Each strategy comes with tradeoffs. Recognizing more income
can increase Medicare premiums, make more Social Security
benefits taxable, or push capital gains into a higher tax
bracket. A taxable Roth conversion creates a current tax
cost and cannot be reversed through recharacterization.
Its future benefit is uncertain, particularly if you or
your heirs later face lower tax rates. Charitable tax
benefits also depend on eligibility, deduction limits,
and how a gift is made. These decisions deserve an
individual review with your tax professional.
Today’s Rates, Your Situation
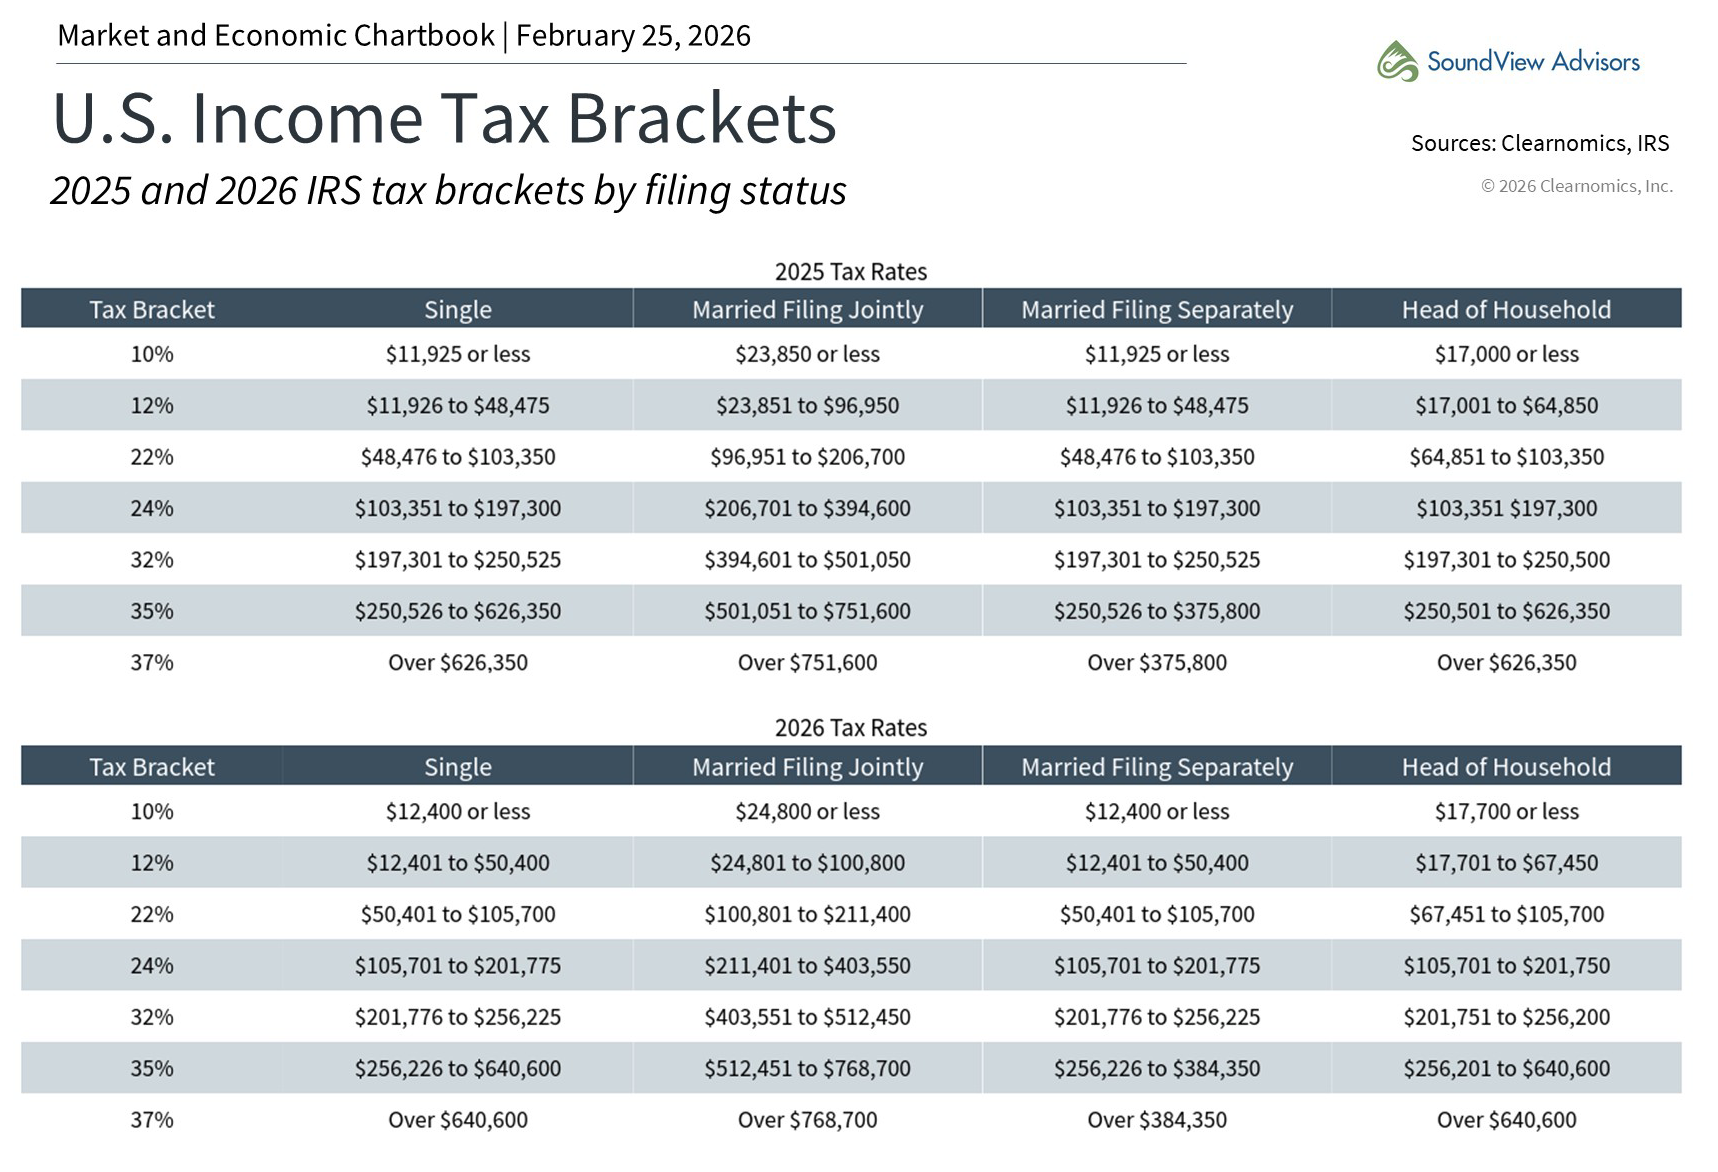
For 2026, federal ordinary income tax rates range from
10% to 37%. The middle brackets are often more relevant
to a planning decision than the highest rate.
2026 Federal Ordinary Income Tax Brackets
Marginal Rate
Single
Married Filing Jointly
10%
Up to $12,400
Up to $24,800
12%
Over $12,400 to $50,400
Over $24,800 to $100,800
22%
Over $50,400 to $105,700
Over $100,800 to $211,400
24%
Over $105,700 to $201,775
Over $211,400 to $403,550
32%
Over $201,775 to $256,225
Over $403,550 to $512,450
35%
Over $256,225 to $640,600
Over $512,450 to $768,700
37%
Over $640,600
Over $768,700
Source:
IRS, tax year 2026 inflation adjustments, October 9, 2025
.
These brackets apply to taxable ordinary income after
deductions, not gross income. Each rate applies only to
income within that bracket. Long-term capital gains and
qualified dividends have separate rate schedules.
Other filing statuses, state taxes, and additional taxes
are not shown.
The 2025 tax law removed the scheduled expiration of the
current individual rates. That doesn’t prevent Congress
from changing them later, but it does mean there is no
automatic rate increase waiting at the end of the current
schedule. Historical rates alone don’t tell us whether
your future tax rate will be higher or lower.
Planning Across a Lifetime
None of us knows where tax policy will be ten or twenty
years from now. Effective planning considers this year’s
bill alongside the taxes you may pay throughout retirement
and the assets you hope to leave to others.
Sometimes paying taxes strategically today can reduce
the taxes you and your heirs pay over the long run.
Whether it does depends on your circumstances, future
tax rates, investment results, and how the strategy is
carried out. Paying more today does not guarantee
paying less overall.
This fall, we’ll revisit your tax strategy as part of your
overall financial plan. We’ll consider the timing of income
and deductions alongside your cash flow, investment,
estate, and charitable goals. The aim is to make thoughtful
decisions with the information we have—and leave room to
adjust as your life and the rules change.
Twenty years ago, I lived near the Tacoma Narrows Bridge and enjoyed watching the construction of the second span. As a boy, I lived about 50 miles from what I think is the most beautiful bridge in the world, the Golden Gate. My family lived to the north and my favorite uncle and his family lived in San Francisco, and we drove across the Golden Gate countless times.
The Day the Span Bowed
Crowds cross the Golden Gate Bridge during its 50th anniversary celebration in 1987.
A few years back I arrived early for a conference in San Francisco and took the opportunity to walk across the nearly two miles of the bridge; there’s a sidewalk and always scores of people doing it. However, for the 50th anniversary of the bridge in 1987, they actually closed the bridge deck to vehicles for 4 hours to allow pedestrians to walk the bridge.
Reports vary from 20,000 to 80,000 as the number expected by officials; the actual attendance was estimated by the California Highway Patrol as 800,000! There were 300,000 people on the span itself for much of this time, and the characteristic convex shape of the bridge was actually flattened by seven feet at mid-span!
People reported the bridge groaning in the wind, but engineers subsequently determined the bridge was not in danger of failure. (Despite this, I note the past 40 years haven’t seen any more mass celebratory walks scheduled across the Golden Gate!)
Bridges are symbols of optimism, of work to create connections, of the possibility of collaboration.
Connections That Serve You
Yes, we love bridges! This fall, our planning focus is on tax management, a planning discipline that rewards connections and collaboration—between advisor and client, between client and tax preparer, and between advisor and tax preparer.
Advisor and Client
Client and Tax Preparer
Advisor and Tax Preparer
Good bridges between you and members of your professional advisory team are vital.
Our advisors stay very current on tax law and see tax management as a key piece of financial planning. A couple of us are CPAs and one is so nerdy as to actually have a master’s degree in taxation. Yet, we believe it is critical that you complement our counsel by having a strong relationship with a competent and responsive tax preparer.
We have no doubt that you are best served when the bridge between us and your tax advisor is strong, reflecting a spirit of professional collaboration and shared intent to serve you well as a team. If you have questions about this relationship or suggestions for us, we welcome your input so this bridge can be strong.
Market highs can feel like warning signs. History suggests they are often a normal part of long-term investing.
by Austin Boyce, Advisor, CFP®
The halfway point of the year provides a natural opportunity to reflect on what has happened so far and consider what may lie ahead in the months to come.
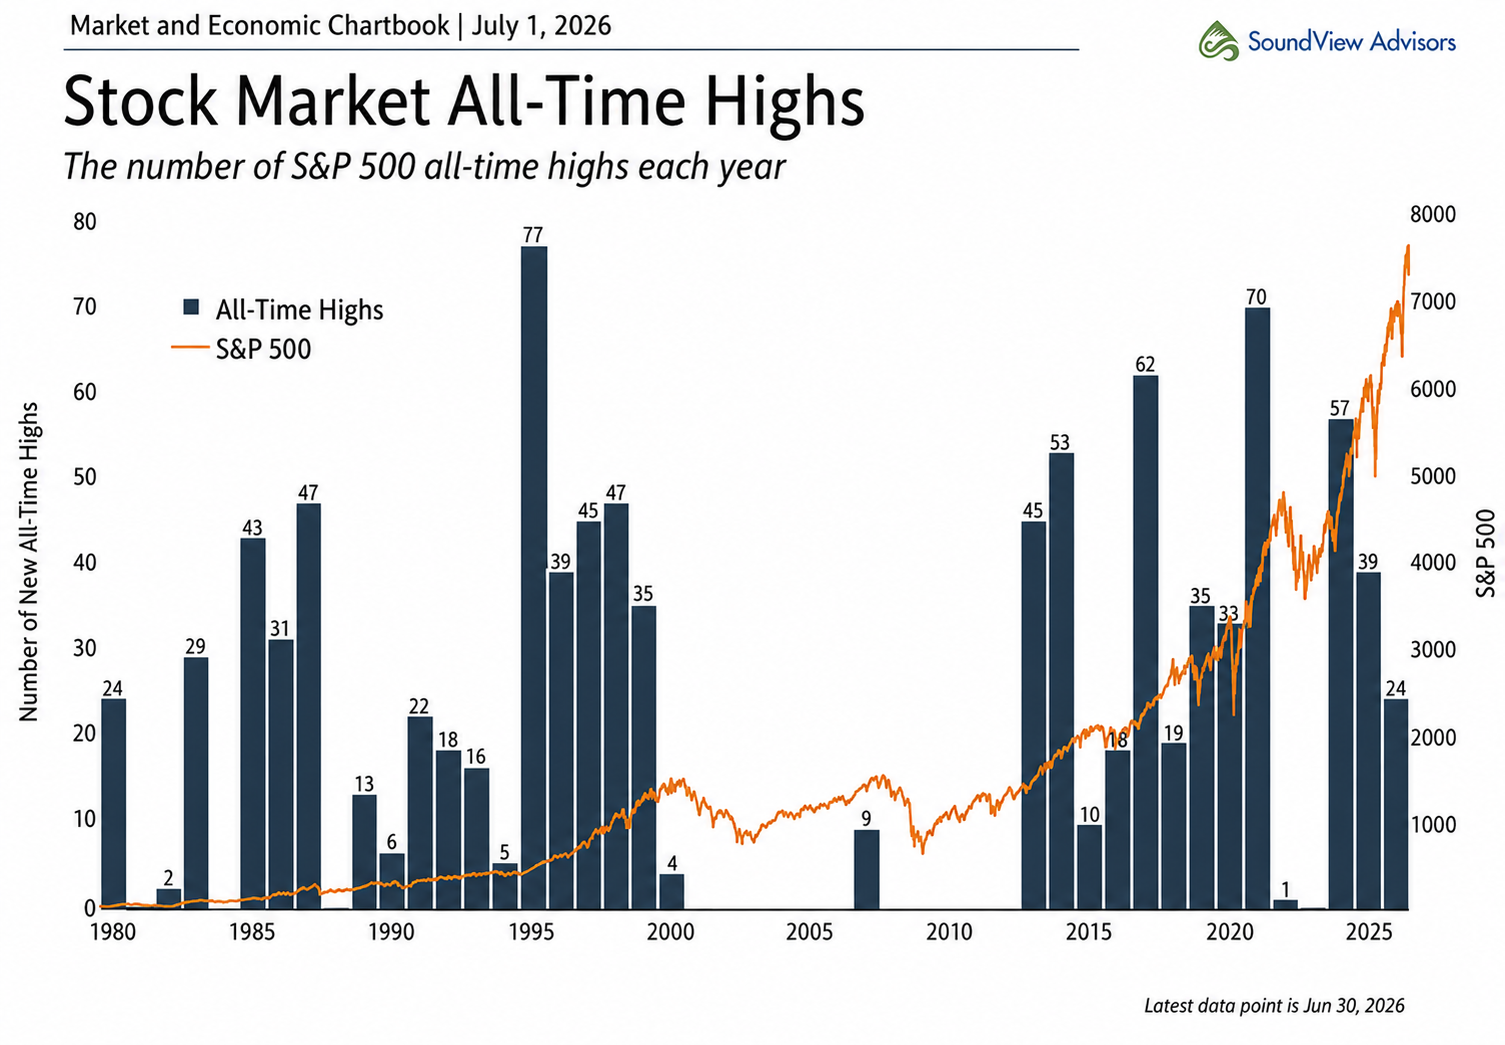
The first half of 2026 delivered its fair share of financial headlines and market surprises. Despite the volatility and uncertainty along the way, the S&P 500 continued to climb to new heights. Through June, the index has recorded 24 new all-time highs.
For investors, market highs can create mixed emotions. On one hand, it’s encouraging to see markets grow and reach new milestones. On the other, it is natural to wonder, "What if this is the peak?" and worry that a market correction may be just around the corner.
Source: Clearnomics and Standard & Poor’s.
Market and Economic Chartbook, July 1, 2026.
Data through June 30, 2026. Chart reproduced by SoundView Advisors.
All-time highs are based on daily closing values.
The S&P 500 is an unmanaged index shown for illustration. It cannot be invested in directly and does not reflect fees or expenses. Your portfolio is diversified across different investments, so its performance will differ from the index. Diversification helps manage risk but cannot guarantee a profit or prevent losses.
Looking at the chart above, however, we can see that reaching multiple new highs within a year is perfectly normal. In fact, some of the market's strongest years have produced dozens of record highs. For example, 1995 saw 77 new highs, followed by another 39 in 1996.
Of course, there have also been periods when new highs were scarce. During the early 2000s, investors experienced several years without seeing the market reach a new record. For those who were able to keep investing, lower prices offered a chance to buy more shares along the way. The market eventually recovered, but it took years—and each investor’s experience depended on their own portfolio and circumstances. History can offer perspective, but it can’t tell us what will happen next.
As we reach the midpoint of 2026 with 24 new all-time highs already recorded, no one knows whether we are in the midst of another extended bull market or approaching a period of more modest returns. The reality is that the future remains uncertain.
Rather than attempting to forecast short-term market movements, we focus on the factors we can control and maintain a long-term perspective.
Your SoundView Advisor is here to help with any questions about your portfolio or financial plan. Our aim is to provide clarity and direction as you navigate the road ahead.
This article is for informational and educational purposes only and is not individualized investment, tax, or legal advice. Investing involves risk, including the possible loss of principal. Past performance does not guarantee future results.
SoundView Advisors is an investment adviser registered with the U.S. Securities and Exchange Commission. Registration does not imply a particular level of skill or training. Additional information about our services, fees, and potential conflicts of interest is available in our
Form ADV Part 2A Brochure.
Saving for retirement takes discipline. Learning to enjoy what you’ve saved can take practice, too.
by Austin Boyce, Advisor, CFP®
Retirement is not a destination. It is the final leg of the road trip we call life. And like any long journey, it comes with its own challenges and opportunities.
The most obvious concern is running out of fuel. In retirement, that fuel is your savings and investments. But there is another, less-discussed risk: reaching the end of the journey with money you could have used for experiences that are no longer possible.
The fear of running out of money is understandable. In AARP’s 2026 Financial Security Trends Survey, 60% of Americans age 50 and older worried about having enough money to last through retirement. Among those who had not yet retired, 42% reported retirement savings below $50,000.
Given those realities, headlines about America’s retirement savings gap make sense. But for someone whose financial plan supports their needs and goals, another question deserves attention: Are they making room to enjoy what they’ve worked so hard to build?
Learning to Spend
A successful retirement plan should make room for both security and meaningful experiences.
Spending in retirement can be surprisingly difficult. After decades of saving and delaying gratification, shifting into a spending mindset does not come naturally. Giving yourself permission to enjoy what you’ve saved can take some getting used to.
Money is a tool. It can give you the freedom to live life on your terms, spending your time how you want, with the people you care about most.
While running out of money can force difficult lifestyle adjustments, underspending carries its own consequences. Retirees may later regret missed opportunities: more travel, greater generosity with family or charities, a vacation home, or experiences they continually postponed.
Finding the right spending rate is a balancing act. Spend too much, and you risk long-term security. Spend too little, and you may pass up meaningful experiences that cannot be recovered.
Leaving money to family or a cause you care about can be an important part of the plan, too. The goal is to make those choices deliberately, with room for both the life you want to live and the legacy you hope to leave.
Rules of Thumb Have Limits
Consider the commonly cited 4% withdrawal rule: withdraw 4% of your portfolio in year one, then adjust that dollar amount for inflation each year. On a $1,000,000 portfolio, that is $40,000 in year one and $40,800 the next if inflation runs 2%.
That gives you a starting framework, but it cannot tell you what your own retirement will require. Your investments, taxes, expenses, and retirement timeline all matter. A fixed formula also cannot know when you want to take a special trip, help a family member, or set more aside for future care.
Those decisions deserve more than a rule of thumb. They deserve a plan that connects your resources with your priorities—and another look as your circumstances change.
Your Individualized Strategy
At SoundView, we take a personalized approach. Every client has different goals, spending needs, family circumstances, and legacy objectives. We help you build a spending strategy designed to balance financial security with living well.
Every plan rests on assumptions about investment returns, inflation, and how long retirement will last. Those assumptions can change, and no spending strategy can guarantee your money will last a lifetime. That’s why we revisit the plan with you along the way.
Think of your advisor as the adaptive cruise control for your financial road trip—helping you assess when there may be room to increase your spending, when to ease back, and when to stay the course.
For every client, that answer is deeply personal. And that is exactly where we start.
As global attention turns toward international competition this summer, it is also a useful moment to consider how global markets interact beyond company fundamentals, particularly through currency.
The U.S. dollar has been on a rollercoaster over the past several years, reflecting shifting expectations around global economic growth, inflation, and central bank policy. While currency movements can feel like background noise, they play a more meaningful role in investor outcomes than they are often given credit for.
A stronger dollar
Can work against international investments when foreign returns are translated back into U.S. dollars. It can also reduce reported earnings for U.S. companies with meaningful overseas revenue.
A weaker dollar
Tends to support international returns and can improve U.S. competitiveness abroad by making U.S. goods and services less expensive for global buyers.
In the same way international competition often turns on conditions and timing rather than a single dominant force, these dynamics are a reminder that investing globally is about more than company fundamentals; it is also about participating in different currency cycles that move over time.
Those cycles are influenced by shifting growth trends, interest rate environments, and global capital flows.
Rather than trying to forecast currency direction, the more durable lesson for investors is simple: global markets are interconnected, and leadership rotates.
Staying diversified across regions and currencies helps reduce reliance on any single outcome and keeps portfolios positioned for a range of environments over time.
Diversification cannot eliminate uncertainty, but it can reduce dependence on any single country, currency, or market cycle.
Over the next few weeks, our perspective may become a bit more
international as we focus on football in Seattle. No, not the
Seahawks, silly—the World Cup.
As we try to find timely hooks that will entice you to read our
newsletter, this seems like an apt moment to share an article
with an international flair. So here goes.
Last year, I could have gone to my high school class’s 50-year
reunion, which means I am starting to think I may be able to
claim a perspective based on long-term experience. Let’s look
together at a few aspects of investing over the past 50 years.
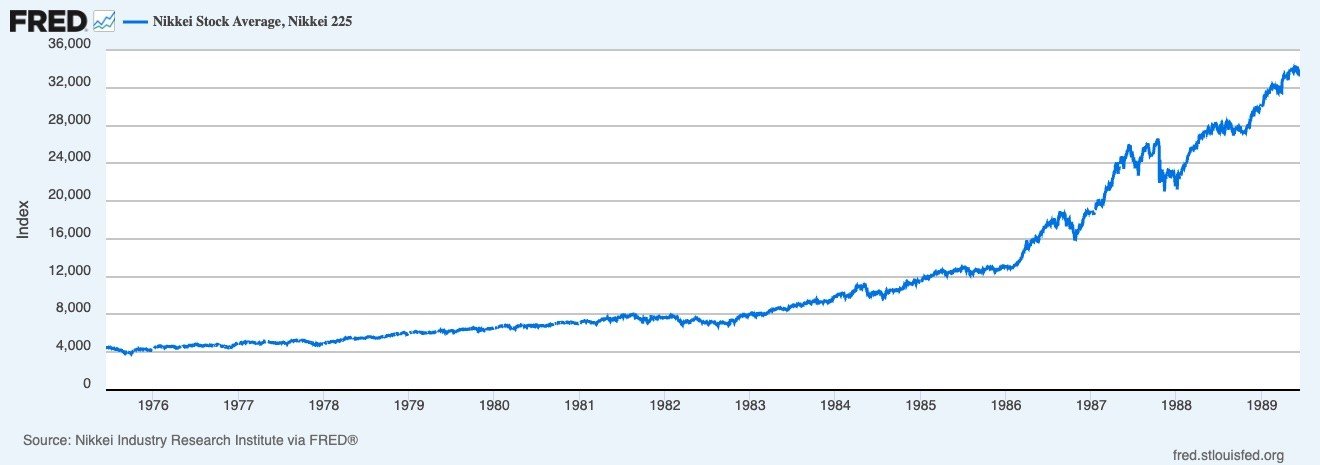
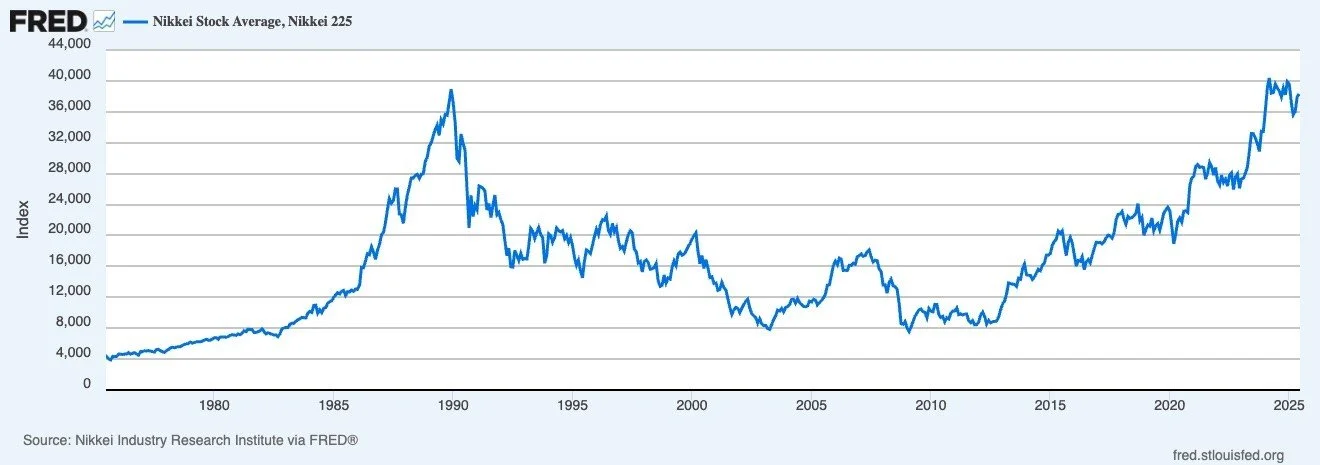
I was curious and used data available through the Federal Reserve
Bank of St. Louis to look back over that period. If I had looked
at the history from when I graduated high school in 1975 to
business school in 1989—yes, I managed to cram four years of
college into 14 years—the Nikkei 225, a Japanese stock market
index, would have looked pretty appealing.
Nikkei 225, 1975–1989.
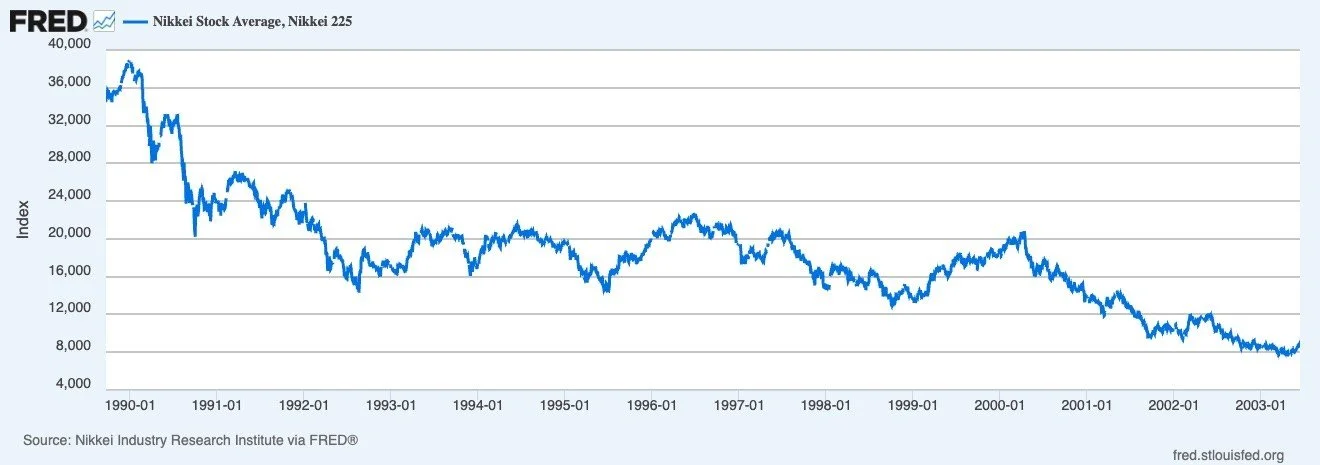
Nikkei 225, 1989–2003.
Source:
Nikkei Industry Research Institute via FRED.
These charts show the nominal price index in Japanese yen.
They exclude dividends and do not represent an investor’s
total return. Select either chart to enlarge it.
So, what would the next 14 years of that market’s history
have looked like?
Not as good as I might have hoped. Truth be told, after
celebrating my college graduation along with the Japanese
market celebrating its all-time high, both of us would have
some challenging times ahead.
Indeed, though 14 years might seem like a long-term investment
horizon, the Nikkei’s price index would need roughly two more
decades to regain its 1989 closing high.
Yes, following that December 1989 peak, the Nikkei 225 did not
surpass its previous closing record until
February 22, 2024—more than 34 years later.
That is a long time to wait.
There is an important distinction here: this is a price-index
story, not the experience of an actual investment account.
Reinvested dividends, changes in the yen’s value against the
dollar, inflation, fees, and taxes would all affect an investor’s
results. Still, it is a useful reminder of how long one country’s
stock market can struggle after an extraordinary run.
So this article is supposed to be about why we invest
internationally, right? How am I doing so far?
The point of that story is that a compelling track record can
make it awfully tempting to put too much faith in one market.
That temptation can apply to Japanese stocks, U.S. stocks,
or whichever market happens to be having its moment.
We don’t include international stocks because we know they
will lead next year. We include them because we don’t know
which country’s market will lead over the years ahead—and
we don’t want the whole plan to depend on getting that answer
right.
Diversification Is About Risk, Not Just Return
The goal of diversification, including international stock
diversification, is to help manage risk. It won’t necessarily
increase returns, and it cannot prevent losses.
When we think about a loss, two questions matter:
Depth: How much value have we lost?
Duration: How long might it take to recover?
Financial author and Northwest native
William Bernstein
describes a related distinction between shallow risk and deep risk.
Shallow risk involves temporary declines. Deep risk involves a
prolonged or permanent loss of purchasing power.
Temporary declines are uncomfortable enough. At SoundView, we
try to help clients navigate them with perspective, a plan,
and the discipline to follow it. That also means thinking
ahead about the money you may need to spend while markets
are down.
A decline that stretches on for years presents a different
challenge. In my experience, more than a decade of disappointing
results can test even a patient investor. Diversification is
one tool we use to help manage that possibility, alongside
an appropriate mix of investments and a realistic spending plan.
International Stocks and Deep Risk
So, what can history tell us about international stocks
and those longer stretches of disappointment?
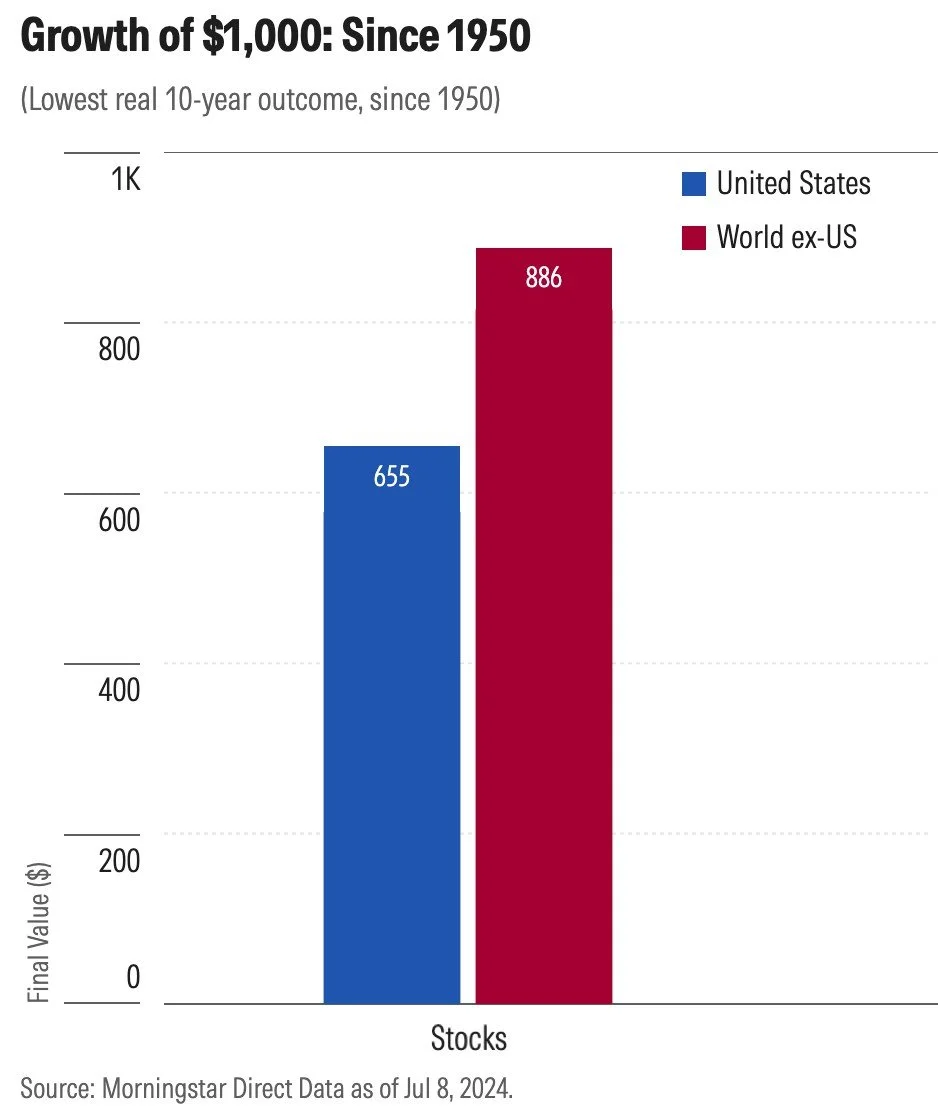
Stock portion of Morningstar’s historical comparison.
Source: John Rekenthaler,
Why International Investing Makes Sense for Long-Term Investors,
July 9, 2024. Morningstar Direct data as of July 8, 2024,
using Dimson–Marsh–Staunton historical U.S. and world
excluding U.S. equity series.
In Morningstar’s comparison, the lowest inflation-adjusted
10-year outcome since 1950 left $1,000 at
$655 for U.S. stocks and
$886 for stocks outside the United States.
These are historical market results measured in U.S. dollars,
including reinvested income.
Each figure represents that market’s own worst 10-year
period; the two periods need not coincide. It doesn’t mean
international stocks fared better in every downturn. In
the study’s earlier sample, covering periods beginning
before 1950, the worst outcome for international stocks
was more severe than for U.S. stocks.
We see this history as one reason to spread our exposure
across countries. It gives us another way to think about
risk, but it cannot tell us how the next difficult decade
will unfold.
International investing brings risks of its own, including
currency changes, political and regulatory developments,
and differences in accounting standards and market liquidity.
International stocks can underperform U.S. stocks for
extended periods, and both can fall at the same time.
Our aim is to help you pursue your goals without making your
financial future depend too heavily on one market. From that
perspective, we believe international stocks can earn a place
in a diversified portfolio. The appropriate mix depends on
your circumstances, time horizon, and willingness and ability
to take risk.
So until we can get back to Seahawks football, find an
opportunity to enjoy some of the World Cup and reflect
on the joys of being international.
Important information:
This article is for general educational purposes and is
not a personalized investment recommendation. All investing
involves risk, including the possible loss of principal.
Past performance does not guarantee future results.
Diversification does not ensure a profit or protect against
losses in a declining market.
The charts illustrate historical market data, not the
performance of SoundView Advisors or any client account.
The Nikkei charts show a price index without dividends;
the Morningstar comparison uses inflation-adjusted historical
equity returns. These presentations use different methods
and should not be treated as directly comparable investment
results. Indexes are unmanaged and cannot be invested in
directly. Actual investment results would be affected by
portfolio holdings, investment timing, advisory fees,
transaction costs, and taxes.
Help! I need somebody, Help! Not just anybody, Help! You know I need someone, Help!
A client was talking with a friend who had told her, “Just call Krista – she’ll help you with that – she helps us with everything.” While that is the compliment of a lifetime, it left me reflecting on the idea of help itself.
I am in a helping profession – perhaps because I have struggled to ask for help (and have seen others do the same). There is something about helpers that puts us at ease. As Fred Rogers once said “Look for the helpers. You will always find people who are helping.”
The need for help changes over our lifetime, but the struggle seemingly does not. The Beatles captured this in their song “Help” decades ago:
When I was younger, so much younger than today, I never needed anybody's help in any way, But now these days are gone and I'm not so self assured, Now I find I've changed my mind, I've opened up the doors.
As children, we often feel surrounded by too many helpers. We assert ourselves, claiming our independence in small ways. Many a parent has wearied over the words “MINE,” “NO,” and “ I CAN DO IT MYSELF.” Those early boundaries matter - they shape how we learn to both give and receive support.
As we grow into adulthood, independence becomes the armor we wear to conquer the world….or at least our little corner of it. We begin to build relationships and navigate responsibility. We still ask for help but it tends to be more practical: moving a couch (PIVOT!), share a ride, work through a problem. We establish and develop what we hope will be lifelong relationships and values.
Help me if you can, I'm feeling down, And I do appreciate you being 'round, Help me get my feet back on the ground, Won't you please, please help me?
Then something shifts. One day we wake up and realize “Uh oh – I’m the person who’s supposed to be the adult now. I’m the person who is supposed to know the things.” This comes with a quiet pressure to have it all together, to be the helper instead of the helped. And yet that’s often when we need help the most.
Humility becomes the agent for growth. We dive into asking for the help we didn’t know we needed. The help that we don’t quite have words for. We learn that growth doesn’t come from having all the answers, but instead from asking the right questions.
And now my life has changed in oh so many ways, My independence seems to vanish in the haze, But ev'ry now and then I feel so insecure, I know that I just need you like I've never done before.
And before we know it, we are in the winter of our lives and the concept of help changes again. Others begin “helping” and the independence we once knew begins to fade. This can lead to feelings of discomfort as help becomes less about choice and more about need.
I share this with you because at SoundView, we are, at our core, the helpers.
Yes, our work is financial – but in reality life is rarely only about the numbers, the answers or a perfect solution. It’s about knowing you don’t have to figure things out alone: perspective, partnership, and a willingness to listen are valuable tools on life’s journey. Each member of our staff has walked their own path, experienced their own challenges, and carried their own losses.
Kamryn Hafer is the newest addition to the SoundView team. Originally from Palm Desert, California, she recently made the move to the Pacific Northwest to start a new chapter in her life. I sat down with her this month to learn more about her and what she brings to the team.
KRISTA: Tell me more about your life before SoundView. What adventures have shaped your story so far?
KAMRYN: It has been an adventure! I grew up in the Palm Springs area, which is mostly a vacation and retirement community. I attended UC Santa Barbara and spent time studying abroad in Siena, Italy (near Florence), before moving to Lake Tahoe for a year. Then I taught English in Prague before returning to California to work with Autistic children in Orange County and Sacramento. Add in a couple of years as a dental assistant, and I full-circled back to resort life.
KRISTA: Wowza! And you still managed to squeeze in experience in wealth management? What skills transition well to SoundView?
KAMRYN: Yes, I spent several years in operations at another RIA, so when I heard that part of the role would involve transitioning client accounts to Fidelity, I knew I had found my moment. Of course, I had to make the interview memorable by joking that I was no longer interested and pretending to get out of my seat. Thankfully, Nate and Lisa “got it,” and we all realized our personalities would work well together.
I don’t think I’ve ever felt more cared for or supported—the collaboration on this team is such a gift.
KRISTA: Any special draw to the PNW? We’re a little different than Palm Springs…
KAMRYN: Yes! My brother and sister-in-law live here. On a very recent visit with them (and my 5-year-old nephew), I felt like it was the right time to transition—I want to be a good Auntie! So, I put a deposit on an apartment and applied for the role at SoundView. Thankfully, the universe aligned with my spontaneity, and as they say, the rest is history.
KRISTA: Can we (or our clients) help with the transition in any way?
KAMRYN: Hmm… I’d love recommendations for vegan restaurants, vintage shops (I collect vintage purses!), and any opportunity to work with animals. I was previously on the board of an animal sanctuary and would love to find a volunteer opportunity again.
This or That?
Streaming or Movie Theater?
BOTH! Movie theaters are nostalgic, and streaming is comfy.
Handwritten or typed?
Handwritten! I’m known for writing letters & birthday cards. My grandma and I have been writing letters to each other since my junior year in high school.
Beer or Wine?
Beer—I prefer citrus and love to embrace nostalgia with beers from countries I’ve lived in. Two memorable examples are enjoying Birra Moretti in Italy and Pilsner Urquell in Prague.
Festivals or Concerts?
Concerts! I’ve been known to travel abroad for a concert. I have eclectic taste in music, so long as it’s live. I recently saw Joseph at the Neptune theatre.
Love or Money?
Oh, LOVE. But we also need money to live. I’m a mushy mush.
Baseball or Football?
Baseball! I try to see stadiums when I travel, and I hear a few SoundView Clients have a similar passion. I grew up playing softball (starting when I was 7) and played travel, varsity, and in college.
Team or Solo projects?
Before coming to SoundView, I would have said solo. But this team has quickly reminded me how much better the adventure can be when you have great people alongside you.
Dogs or Cats?
I have a sweet cat named River. She fell out of a tree at my mom’s office, so I brought her home, bottle-fed her, and was hooked from there. She’s been with me for 18 years (through all of my adventures!) and speaks English, Italian, and Czech 😉
Ben Jennings reflects on a historically low University of Michigan consumer sentiment reading and questions whether today truly warrants such pessimism. Drawing from Hans Rosling’s Factfulness, he explains how gap thinking and negativity bias distort perception, making the world feel worse than it is. He illustrates this with memories of 1970s gas shortages, noting that despite lingering assumptions about foreign oil dependence, the U.S. is now a major net crude oil exporter. His main advice is to curate information: consume less attention-driven media and read longer-form books that provide history, context, and perspective for better life and portfolio decisions overall.
SoundView currently works with three custodians: Schwab, Pershing, and, to a far lesser degree, TIAA-CREF. It’s a long, dramatic story of how we got to this point, but ultimately, we felt it was in everyone’s best interest to ensure multiple options were available.
Beginning in April, we will add Fidelity as a new custodian and eventually phase out our relationship with Pershing. We expect clients to see both an elevated service experience and more competitive long-term costs. We anticipate that most of our Pershing clients will switch to Fidelity. However, your Advisor will discuss the change with you.
Background (for Compliance Geeks!)
SoundView is a Registered Investment Advisor (RIA) as opposed to a broker. This has two key implications. First, we are fiduciaries to our clients—we legally must act in their best interests rather than our own. (That seems like the ethical thing to do anyway, but brokers successfully fought against being held to this standard earlier this year.)
Second, we do not take possession of client assets; rather, we work with custodians that hold clients’ investments in accounts in the client’s name. We direct the custodians on the actions to take with those assets and depend on them to be strong business partners and provide great service to our clients, just like we do.
Transition Teammate
SoundView’s newest team member, Kamryn Hafer, will serve as the point person for this transition. Not only is she a lovely person, but she has experience managing similar transitions at her prior employer and will work closely with your Advisor and Support Advisor to make this as seamless as possible. We anticipate that the majority of accounts moving to Fidelity will be completed by the end of June.
We feel good about this move and what it means over time. We’ll be walking through the transition with you, step by step, and doing everything we can to keep it smooth and straightforward. Our team will handle the heavy lifting behind the scenes, and we’re here if anything comes up along the way.
Spring has a way of bringing things into the light. Longer days, more energy, and a clearer view of what’s been sitting unnoticed. When you open a drawer, you suddenly realize just how many things have been kept without you even noticing. The clutter didn’t arrive all at once. It built slowly, quietly, until it started to feel normal.
Lately, I’ve been living this in real time.
My oldest son is preparing to leave for the Navy, and we’ve spent the past few weeks sorting through his belongings, deciding what to hold on to and what to let go. What’s surprised me most isn’t the physical process, but the conversations. As he steps into a new chapter, he’s also deciding what beliefs, habits, and expectations still fit and which ones don’t.
Less space requires more clarity. His values are becoming the filter.
I see a similar process play out with clients entering retirement.
A Different Kind of Return
After years, often decades, of saving and accumulating, the habits that once served us can be hard to set down. The instinct to optimize, to grow, to assign value to every decision doesn’t just disappear. But this next phase asks for something different. Not everything needs to grow to have value. Not everything needs to be maximized to be meaningful.
The shift from accumulation to spending isn’t just financial—it’s mental. And without intention, it can feel like losing ground, even when nothing is wrong.
Markets add another layer to this. Many of us have grown used to a rhythm of strong returns and steady growth, which quietly shapes what we expect. When reality looks different, it can feel like something is off.
Off, but compared to what?
The Art of Rebalancing
Rebalancing offers a useful parallel. Over time, portfolios drift. What has performed well takes up more space, often without us noticing. Rebalancing simply brings things back into alignment. Trimming what has grown and adding where space has opened. This is not a reaction but a return to intention.
The same can be true for how we think.
Spring isn’t just a time to clear things out; it’s a time to ask what still fits.
What are you carrying forward out of habit?
What beliefs were built for a different season?
What would it look like to realign - not toward more, but toward enough?
Clarity doesn’t come from adding more. It comes from choosing what to keep.
The war between the U.S. and Israel, and Iran feels like it will have significant long-term impacts. How will future oil prices be affected? How will global political alliances shift? How will trade be impacted? These are important questions—and ones to which none of us yet has a clear answer.
Those questions naturally lead to another: Do I need to make changes to my investment portfolio? While we don’t know the full answer, history gives us some perspective—particularly when it comes to the largest holding in most portfolios: large-cap US stocks.
Wars are, by nature, incredibly disruptive. From the chart below, we can see that more often than not, long-term US investors have experienced positive returns despite the chaos surrounding global conflicts. This chart tracks the market return of large US companies one, five, and ten years after various wars begin.
It may be tempting to take a cynical view and attribute this to war profiteering. However, the data shows that returns are often positive even in the short term and tend to improve further after conflicts conclude.
Given this, we are not making any immediate changes to client equity allocations. We remain invested across both US and international markets, recognizing that different outcomes may impact companies and regions in different ways.
On the fixed income side, we have made a small adjustment. As interest rates have risen, we sold BondBloxx 6M US Treasury (XHLF) and purchased Vanguard Core Bond (VCRB) to take advantage of higher yields. We anticipate making one or two similar adjustments within fixed income over the course of the year.
We will continue to communicate as our thinking and strategy evolve. As always, we welcome your questions and conversations as we navigate these times together.
As former Senator Max Baucus once observed, “Tax complexity itself is a kind of tax.” That observation feels especially true in 2026, as significant tax policy changes require attention at the start of the year. From retirement contribution rules to expanded deduction limits, understanding these changes is essential for making informed financial decisions.
Rather than viewing tax policy shifts as obstacles, they can also create opportunities to refine strategies and strengthen long-term plans. Below, we summarize two of the biggest tax changes for the tax year 2026.
Catch-Up Contributions Face New Roth Requirements
One significant change for tax year 2026 involves retirement catch-up contributions. For years, employees age 50 and older have been able to contribute beyond standard limits to boost their retirement savings. This has been especially valuable for those who started saving later or experienced financial setbacks. The standard catch-up amount is $8,500 for those age 50 and older, while a “super catch-up” of $11,250 is available for those ages 60–63.
Starting in 2026, higher earners face a new restriction. Employees with annual earnings of $150,000 or more must now make all catch-up contributions as Roth contributions. While Roth contributions offer tax-free growth and withdrawals in retirement, they provide no immediate tax relief. For those in peak earning years who have relied on catch-up contributions to manage their tax burden, it’s important to evaluate how this change affects their tax planning strategy.
The SALT Deduction Cap Rises Significantly
Another major change expands opportunities for many taxpayers. The state and local tax (SALT) deduction has been raised from $10,000 to $40,400 for 2026. The limit will increase annually by 1% through 2029, before reverting to $10,000 in 2030.
When the SALT cap was set at $10,000 in 2017, it dramatically reduced the number of itemized deductions. Combined with the doubled standard deduction, the percentage of taxpayers who itemized fell from about 30% before 2017 to just 10% in 2022. Now, many more households may find that itemizing saves money.
Consider a married couple with $35,000 in state and local taxes, $8,000 in charitable giving, and $12,000 in mortgage interest. Under the previous $10,000 cap, their itemized deductions totaled $30,000—less than the $32,200 standard deduction. Under 2026 rules, they can deduct the full $35,000 in state and local taxes, bringing itemized deductions to $55,000.
The expanded SALT deduction creates strategic opportunities. If you're close to the itemizing threshold, strategies such as bunching charitable contributions, prepaying property taxes (where allowed), or timing other deductible expenses may help increase deductions.
Taxes play a key role in long-term financial success, and the changes in 2026 provide a great opportunity to review your situation and determine whether additional strategies should be considered. We look forward to discussing these changes with you throughout the year. If you have questions in the meantime, please don’t hesitate to reach out.